


Buying and maintaining a home is expensive — and the cost just keeps climbing. Fortunately, Uncle Sam offers several tax breaks that can put more money back in a homeowner’s pocket.
Some of these deductions and credits can only be used by a small slice of homeowners nationwide. But others are available to a wider swath of folks.
Following are federal income tax breaks for homeowners that can ease the sting of homeownership costs.
1. Energy-efficient home improvement credit
If you have made specific energy-efficient improvements to your home, you might qualify for this tax credit. Qualifying expenses can include:
- Qualified energy-efficiency improvements installed during the year
- Residential energy property expenses (such as new central air conditioners; natural gas, propane or oil water heaters; and natural gas, propane or oil furnaces and hot water boilers)
- Home energy audits
Through 2032, this credit is worth up to 30% of the cost of eligible property, up to a limit of $1,200 per year.
Note, though, that it is a nonrefundable tax credit — the less useful of two main types of tax credits.
The other main type of tax credit, refundable tax credits, can increase your tax refund or result in your receiving a refund even if you didn’t owe taxes. But a nonrefundable tax credit like the energy-efficient home improvement credit can only lower your tax bill. That means if you don’t owe the IRS for the tax year during which you purchased eligible energy-efficient property — in other words, you receive a tax refund for that tax year — this tax credit won’t help you at all. It’s effectively worthless to you.
2. Residential clean energy credit
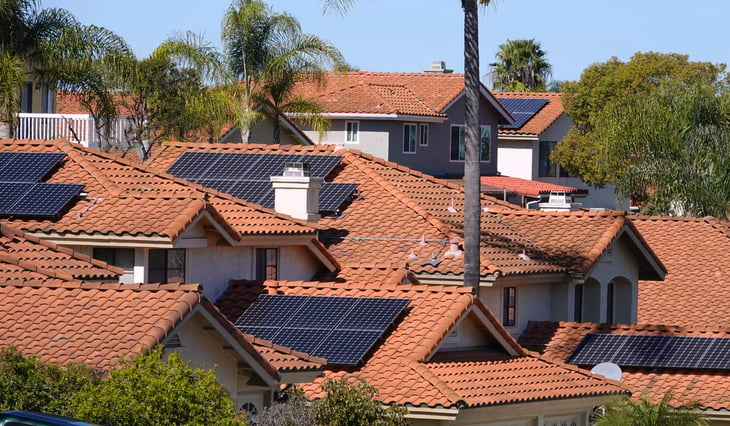
This tax credit is for homeowners who invest in renewable energy. Qualifying expenses can include:
- Solar electric panels
- Solar water heaters
- Wind turbines
- Geothermal heat pumps
- Fuel cells
- Battery storage technology
The residential clean energy credit is available through 2032 and is worth up to 30% of the cost of qualifying new clean-energy property. But like the energy-efficient home improvement credit, it’s nonrefundable. So, it won’t help you unless you owe taxes, as opposed to receive a refund, for the tax year during which you purchase qualifying clean-energy property.
3. Capital gains exclusion when selling your home
Selling your home opens the door to one of the most generous breaks in the entire U.S. tax code.
Currently, single homeowners who sell and enjoy a capital gain — that is, profit earned from the sale — may qualify to exclude up to $250,000 of that gain from their income. That means they won’t owe federal income taxes on that profit.
If you are married and file a joint return with your spouse, the exclusion jumps to $500,000.
There are some rules you must follow to get this break. For example, the IRS requires you to have owned and used your home as your main residence for at least two years during the five years prior to selling it.
Other rules apply — such as that you generally are ineligible if you excluded the gain from the sale of another home during the two-year period prior to the sale of your current home.
For more, check out this page on the IRS website: IRS Topic No. 701, Sale of Your Home.
4. Net investment income exclusion when selling your home
The net investment income tax, which started in 2013, is a 3.8% tax that generally applies to income such as interest, dividends, capital gains, rental and royalty income, and non-qualified annuities.
Not everyone pays it, though. Your income needs to be above a certain threshold, which is currently set at:
- $250,000 for people whose tax-filing status is married filing jointly or surviving spouse with a dependent child
- $200,000 for the filing status of single or head of household
- $125,000 for the filing status of married filing separately
However, even for those who owe the tax, there is an exception for gains on the sale of a personal home. If such a gain is excluded from your gross income for regular income tax purposes, it also is excluded from your net investment income for the purpose of the 3.8% tax.
5. Exclusion for canceled mortgage debt
Debt forgiveness is a rose that often comes with a thorn — in the form of taxes you owe on the debt that has been canceled. This is because the IRS often considers a canceled debt to be taxable income.
However, a federal law known as the Mortgage Forgiveness Debt Relief Act of 2007 “generally allows taxpayers to exclude income from the discharge of debt on their principal residence,” according to the IRS.
This relief applies to debt reduced through mortgage restructuring and mortgage debt forgiven in connection with a foreclosure. It allows up to $750,000 in forgiven debt to be excluded, depending on your tax-filing status.
This provision of the 2007 law was originally intended to be temporary but has since been extended through 2025.

6. Deduction for mortgage interest

The deduction for mortgage interest allows you to write off the interest you pay on a mortgage loan. It applies to interest on mortgages for first and second homes and refinanced mortgages. The IRS defines “home” pretty broadly — it even includes a house boat.
If you took out your mortgage on or before Dec. 15, 2017, you can deduct interest on a debt of up to $1 million. For homes purchased anytime from Dec. 16, 2017, through the end of 2025, only interest applied to loan amounts of up to $750,000 can be deducted.
This tax break — and all that follow on this list — are what the IRS calls itemized deductions. That means you can take advantage of them only if you itemize your deductions as opposed to claiming the standard deduction. The vast majority of taxpayers are better off claiming the standard deduction than itemizing, however, so itemized deductions like this one won’t help most people.
7. Deduction for home equity loan interest
Just as you can deduct the interest from a mortgage loan if you itemize, you also can deduct the interest on a home equity loan or home equity line of credit.
However, under current law, the interest is only deductible if the loan was used to “buy, build or substantially improve your home that secures the loan,” according to the IRS.
So, you’re out of luck if you use a home equity loan to cover living expenses or pay off debts, for example.
8. Deduction for real estate property taxes
Currently, those who itemize generally can deduct up to $10,000 of their state and local taxes, including real estate property taxes.
The $10,000 cap on this deduction is set to expire at the end of 2025, at which time the cap will be removed entirely, which would make the deduction more valuable, unless Congress adopts legislation that says otherwise before Dec. 31. Making this deduction more valuable was also a campaign promise of President Donald Trump, as we detailed in “8 Groups Who Can Expect New Tax Breaks Under Trump.”
9. Medical expense deduction for home improvements
One last tax break for those who itemize: Some home improvements can be deducted as medical expenses if they meet certain criteria. According to the IRS:
“You can include in medical expenses amounts you pay for special equipment installed in a home, or for improvements, if their main purpose is medical care for you, your spouse, or your dependent.”
Just note that this deduction only applies to the part of your medical and dental expenses that is more than 7.5% of your adjusted gross income. So, even if you itemize, you cannot deduct the full value of your medical expenses.
You can find more details in IRS Publication 502, Medical and Dental Expenses.

Add a Comment