


Americans sleep well at night knowing the Federal Deposit Insurance Corp. — or FDIC — protects their savings. But could President Donald Trump change that?
Congress established the FDIC in 1933 as an independent federal agency to insure deposits and supervise financial institutions.
Trump is now half a year into his second term and still has yet to appoint a permanent FDIC chair. That reportedly has bankers worried.
This follows other indicators that Trump might change the FDIC.
For example, a February executive order gave the president more oversight over independent federal agencies.
In addition, since Trump took office, the agency has rolled back several regulations established under former President Joe Biden’s administration.
If all of this leaves you nervous about whether the FDIC will continue to protect your savings, know that such fears are likely unwarranted. But if you are nonetheless curious about alternatives to FDIC insurance, here’s what you should know about the FDIC, followed by some of the best places to keep your cash outside of FDIC-insured accounts.
They are among the best places for cash specifically because they offer both relative safety and relative liquidity. That means your money will be about as safe as it can get outside of an FDIC-insured account. But at the same time, your money won’t be tied up long-term like it would be if you invested it in, say, stocks.
How FDIC insurance currently works
Currently, it is likely that most of the money you keep in a bank or credit union is covered by insurance. As Money Talks News founder Stacy Johnson has pointed out:
“The Federal Deposit Insurance Corp. is what insures bank accounts. So, if a bank has FDIC insurance, your accounts are insured up to $250,000. Banking fees support the FDIC. How do you know if your bank has FDIC insurance? You could look for the little emblem on their website, but here’s a better thing to do: Go to FDIC BankFind and see for yourself.”
Here are some of the types of deposits covered by FDIC-insured banks:
- Checking accounts
- Savings accounts
- Certificates of deposit (CDs)
- Cashier’s checks, money orders and other official bank-issued items
This means that as of today, if you choose the right bank, there is virtually no risk of losing at least $250,000 on these types of accounts and deposits. If you are worried about potential changes to the FDIC, though, read on for some alternative safe places to keep your cash.
1. Money market mutual funds

Money market mutual funds are a relatively safe place to keep your money if you don’t want simply to leave it in a bank. Typically available through brokerages, they’re a type of mutual fund that invests in cash, cash equivalents and short-term debt securities.
Stacy has written about using them because they are “low-risk, pay whatever short-term rates allow and keep cash readily available.”
However, it is important to note that, technically, a money market mutual fund is considered to be an investment, albeit one with low risk. Because these are investments, they are not FDIC-insured. That means there is potential for you to lose money, although it’s very unlikely.
Still, there is a history of investors becoming frightened about economic conditions and trying to pull their money from money market mutual funds en masse. In fact, this happened during both the Great Recession and the early stages of the COVID-19 pandemic.
In both cases, the Federal Reserve came to the rescue to prevent a meltdown.

2. Treasury marketable securities
Treasurys are among the safest places to park your cash because the federal government backs them. A Treasury marketable security is a type of security you can transfer to someone else, which makes it different from a non-marketable U.S. savings bond.
You can also sell Treasury marketable securities before they mature, which makes them relatively liquid. There are five types of Treasury marketable securities:
- Treasury bills (which mature in four, six, eight, 13, 17, 26 or 52 weeks)
- Treasury notes (which mature in two, three, five, seven or 10 years)
- Treasury bonds (which mature in either 20 or 30 years)
- Treasury Inflation-Protected Securities (TIPS)
- Floating rate notes
You can bid for (buy) Treasury marketable securities through the Treasury Department’s TreasuryDirect website or through a bank, broker or dealer.
3. U.S. savings bonds
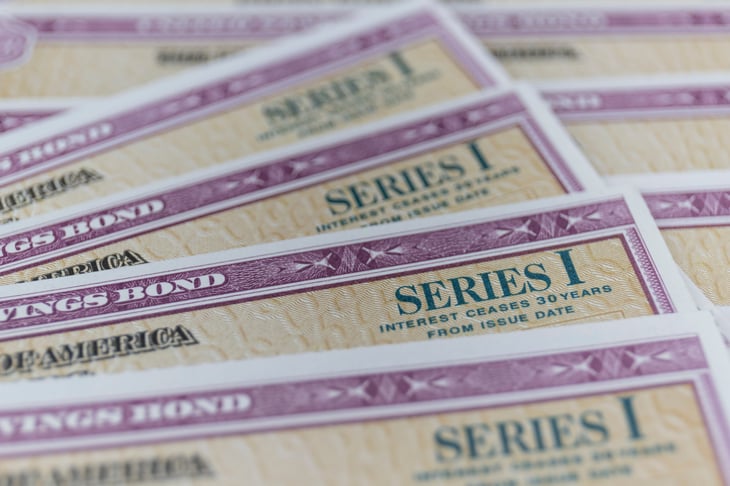
U.S. savings bonds are Treasury non-marketable securities, meaning you cannot transfer or sell them to someone else. The two options currently available are:
- Series I savings bonds: This type of savings bond has an overall rate that is calculated from a fixed rate and an inflation rate. The fixed rate never changes, but the inflation rate is reset every six months. They have a 30-year term, though you don’t have to hold them nearly that long, as we’ll get to.
- Series EE savings bonds: This type of savings bond earns interest regularly for 30 years, or until you cash them. The federal government guarantees the bond will double in value over 20 years.
Unlike marketable Treasurys, savings bonds are not liquid. However, they are just as safe as other Treasurys, and you only have to hold an I bond or an EE bond for 12 months before you can sell it.
You can buy U.S. savings bonds via the Treasury Department’s TreasuryDirect website.

Add a Comment