


Retirement is supposed to be the golden time when you get to relax and enjoy the fruits of decades of labor. But for many of us, the closer we get to retirement, the more we worry.
You worry about outliving your savings. You’re concerned health expenses will erode your nest egg. You have anxiety about a stock market collapse. You fear your family will need unforeseen financial help. And you fret about unanticipated reductions in things like Medicare, Social Security or company pensions.
These are the “Big 5” retirement risks. While we can’t control them, we can prepare for them. Here’s a look at each risk, along with a strategy to defuse it.
Risk 1: Outliving your savings
Retirees are living longer than ever: Sounds great, until you realize it also means you’ll need a bigger nest egg to fund those extra years. Make sure you have enough savings and income to last your lifetime. If you can, delay collecting Social Security. You’ll get up to 32% more monthly if you wait until 70 instead of full retirement age. You might also consider annuities for regular, lifetime income. And try not to withdraw more than 4% annually from investments.
And speaking of investments, if your portfolio isn’t performing as well as you’d like, perhaps it’s time to talk to a pro.
If you’ve got at least $100,000 in investments, check out a free service called SmartAsset. You fill out a short questionnaire and instantly get matched with up to three vetted financial advisors in your area, all legally bound to work in your best interests.
Can a professional advisor make a difference? It’s certainly possible.
One Vanguard study found that, on average, a hypothetical $500,000 investment over 25 years would grow to $1.7 million if you manage it yourself, but more than $3.4 million if you work with a financial advisor. That’s twice as much!
Risk 2: Healthcare costs
Medical bills can quickly eat through retirement savings, especially with the rising cost of healthcare. Medicare doesn’t cover everything, so you’ll need savings or insurance to handle expenses. Use HSAs, Medigap plans, Medicare Advantage plans, and long-term care insurance to shield against crushing expenses.
Without long-term care insurance, your options aren’t great: running through savings, borrowing money, burdening your family with your care, and possibly losing independence because you can’t live on your own.
One place to check out long-term care insurance is GoldenCare. (Unless you live in the four states where GoldenCare doesn’t operate: Alaska, Florida, Hawaii and Washington.)
Risk 3: Stock market declines
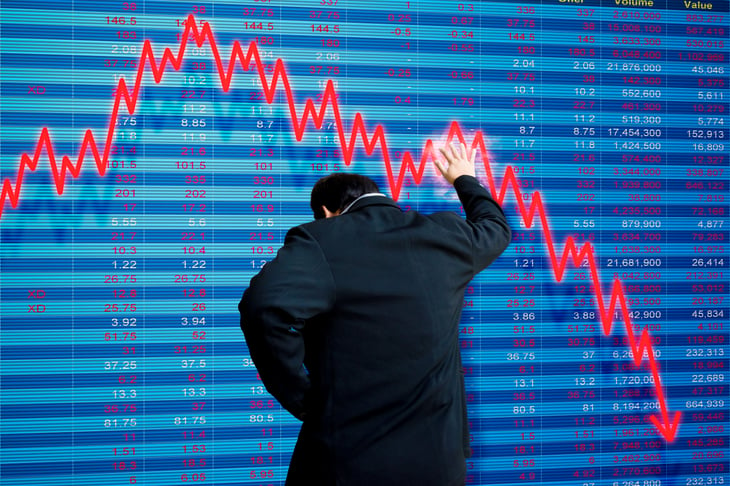
Stocks are an important part of your retirement savings, but they can be a roller coaster. To smooth out volatility, use fixed income assets like bonds, annuities, CDs, and money market funds. These steadier (though lower return) assets allow you to wait out stock swoons instead of being forced to sell at the wrong time.
Lower rates are likely ahead, so this is a good time to lock in today’s higher CD rates. Check out this list of the top 10 CDs and see if you’re earning as much as you can.
Also, rebalance your portfolio regularly to make sure you don’t have too much stock exposure. Finally, as I suggested above, consider talking to professional advisor. You’ll typically get a free first appointment. What do you have to lose? Other than a chunk of your life savings, that is.
Risk 4: Family needs drain your savings
Even grown kids sometimes need financial assistance, and elderly parents may need caregiving. But make sure your generosity doesn’t wreck your retirement. Say no if requests are unreasonable, set boundaries and above all, avoid tapping retirement accounts.
Remember, sometimes the best thing you can do for those in need isn’t money; it’s guidance and advice. In short, don’t give them fish; teach them to fish.
If you’re concerned about protecting your family in case you’re no longer around, you might consider life insurance. It’s not hard to check out.
For example, Ethos is a company that lets you apply online in minutes. No medical exams, no blood tests. And it may cost as little as $7 a month: less than you might be spending now on coffee.
Risk 5: The unknowable
Government benefit cuts, tax law changes, inflation, and more can threaten your retirement security. There’s no way to know what the future will bring.
The only hedge against these risks is to save aggressively, secure company pensions, lock in benefits early, invest wisely and consider inflation-resistant assets.
Stocks are one way to protect against inflation. Another is gold. These days you can even own gold in a retirement account. Don’t go crazy: you shouldn’t have more than 10-15% of your assets in gold, but it’s worth checking out.
Bottom line? The key to lowering risk is anticipating and doing your best to deal, as far in advance as possible, with potential risks to your retirement.

Add a Comment