


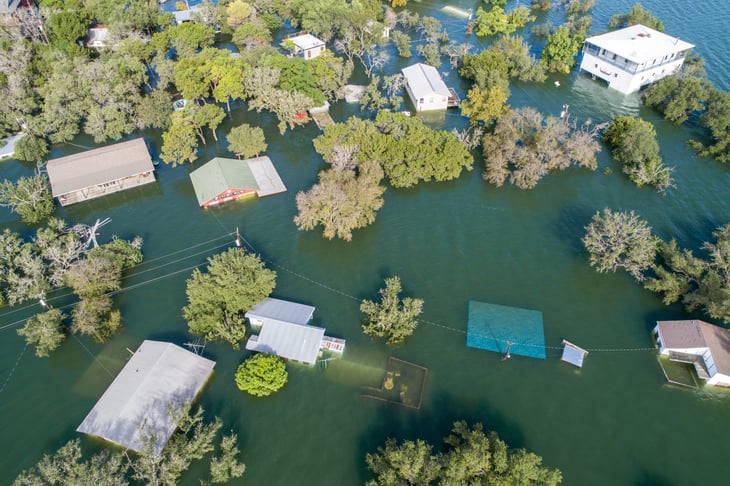
When floodwaters rise, don’t look to your homeowners insurance policy to protect you. Such insurance does not cover damage from floods.
To get protection, you need to purchase a separate flood insurance policy. But even with this coverage, there are some key gaps that could leave you unprotected for specific types of damage caused by flooding.
Here’s a look at what exactly is excluded from coverage by a flood insurance policy.
1. Some damage to your basement
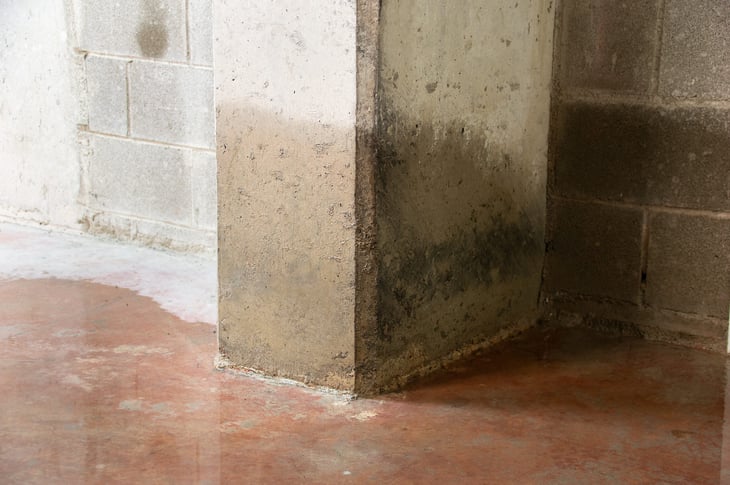
Some elements of your basement fall under the protection of your flood insurance policy. But many others do not.
Items not covered include:
- Personal property, such as couches and TVs
- Improvements to your basement, such as flooring, finished walls and built-ins like bathroom fixtures
- Dehumidifiers that are not integrated into the home’s heating and air conditioning system
- Generators that are not integrated
2. Mold damage
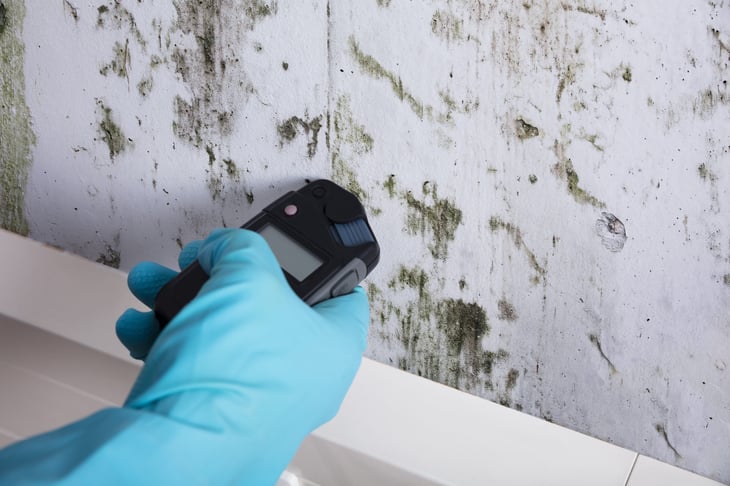
After flooding, it’s important to act fast to prevent the growth of mold and mildew. A quick cleanup is doubly important because flood insurance typically does not cover damage from mold, and postponing mold removal could result in greater damage and thus greater cost later.
Only on rare occasions might mold damage fall under a flood insurance policy’s coverage. This may be the case if, for example, you’re unable to get back to your home because of floodwaters or because officials prevented people from entering your neighborhood.

3. Some valuable items

Flood insurance includes coverage for your personal belongings. However, some valuable items — such as original artwork or furs — are only covered up to $2,500. If you have high-value items, this can leave a big hole in your coverage.
It is also important to note that with flood insurance, you must purchase contents coverage (which covers belongings) and building coverage (which covers structures themselves) separately. Each type of coverage has a separate deductible as well. If you do not purchase contents coverage, none of your belongings will be covered.
4. Landscaping and belongings outside the structure
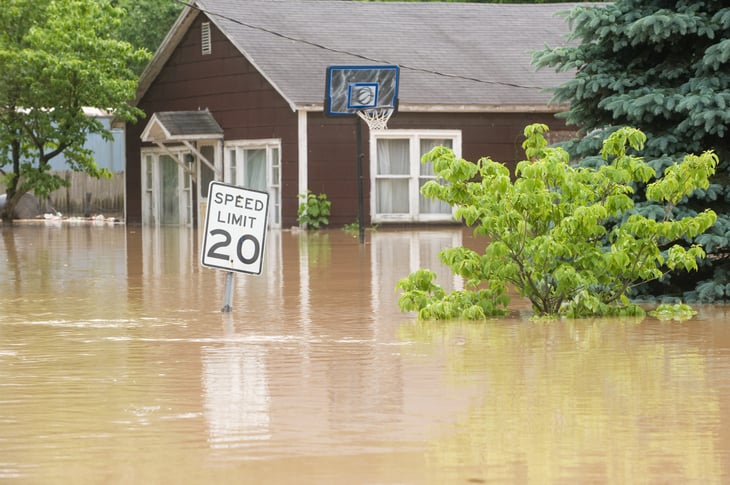
If a flood rolls over your property and destroys trees, decks, fences and pools, don’t expect flood insurance to ride to the rescue.
Items outside the insured structure itself do not fall under the protection of a flood insurance policy.
5. Vehicles
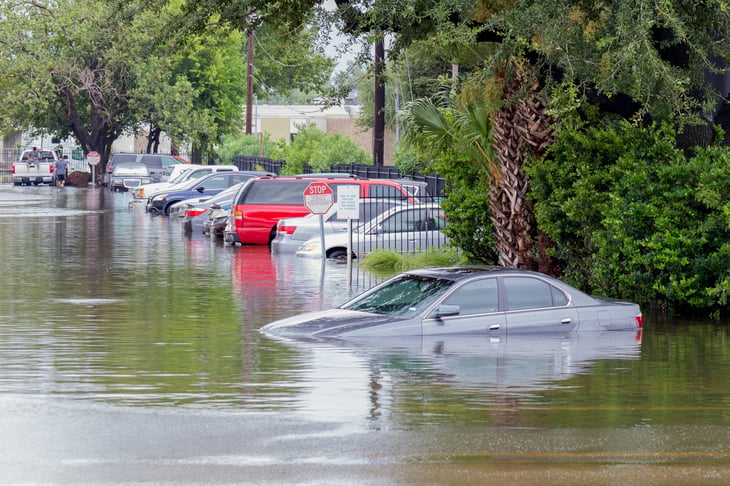
Finally, flood insurance will not cover damage to or the loss of your vehicles.
Fortunately, your auto insurance policy will pick up the tab — but only if you purchased comprehensive coverage. Also, you will have to pay the deductible on your car insurance policy.
If you’re considering changing your auto insurance coverage, be sure to shop around for the best combination of coverage and cost for your situation. Online comparison tools make this easy.

Add a Comment