


Editor's Note: This story originally appeared on Boldin.
We all can do better when it comes to personal finance. In fact, many of the following problems are experienced by 50% of Americans (or more).
How many of these biggest retirement planning mistakes are you making? And what is the impact on your lifestyle now and on your future financial security?
1. You Don’t Know What You Spend Money on Every Month

According to a recent study by U.S. Bank, only 41% of Americans say they use a budget. This is a big mistake – especially as you enter retirement.
When you are working, it is perhaps reasonable that you get by month to month and just do some mental accounting to make sure that bills are paid and accounts are not overdrawn.
However, to have a secure retirement, you need to know how much money you want to spend every month for the rest of your life. And, you can do an infinitely better job with a retirement budget if you know exactly what you actually spend money on now.
Furthermore, monthly budgeting is almost guaranteed to help you identify good opportunities for cutting costs. Little things can really add up. For example:
Some estimates suggest that an average household wastes $1,350 to $2,275 on food each year.
Plus, there are hidden financial fees, errors on your credit card bills, unused subscriptions and more.
Easy fix: Take one hour this week and write down everything you have spent money on in the last month. Categorize your spending. And then, do this for a few months in a row. Use this knowledge to make a better retirement plan.
2. You Own Too Much House

Reports suggest that the size of the average American house has more than doubled since the 1950s. What’s worse are the huge sacrifices we make to afford to live in these homes.
According to a report by the MacArthur Foundation, between 2011 and 2014, more than half of all Americans made at least one major sacrifice in order to cover their rent or mortgage payments. And, when they say sacrifice, they don’t mean skimping on eating out or a weekend away.
To afford housing, 52% of households took on a second job, did not save for retirement, avoided medical care and/or ran up credit card debt.
Easy fix: Experts suggest that you should spend no more than 30% of your gross income on housing.
If you own, retirement is the ideal time to consider relocating and downsizing to a more affordable home. As your biggest expense and most valuable asset, downsizing can have a massively positive effect on your retirement finances.
3. Not Following the Savings Playbook
You have a lot of demands on your money. And, once you have expenses covered, you have a lot of choices for what to do with the excess: HSAs, Roth, traditional, extra mortgage payments and more.
The Savings Playbook provides a rational order of priorities to ensure that you’re using your money in the most impactful way. Start with making sure you have an adequate emergency fund. Once that is done, max out your employer match at work, and so on through 8 steps.
Easy fix: If you want to simplify your decision-making around savings, try the savings playbook. Learn more here.
4. You Don’t Have an Investment Policy Statement

When it comes to your retirement investments, you will likely do best with a defined strategy. An Investment Policy Statement (IPS) is a document that defines your investment goals, strategies for achieving the goals, a framework for making changes to your plan, and options for what to do if things don’t go as expected.
A good IPS should ensure better financial outcomes, especially if all involved parties understand the document. An IPS is especially useful during stock market crashes and when you experience a major life change or transition.
As Ben Carlson of the blog A Wealth of Common Sense told Steve Chen, founder of Boldin, in a podcast:
“…it’s really about understanding yourself, your own emotions and to a higher extent your lesser self, and understanding what doesn’t work for you. And so, if you can filter out all the bad stuff and the stuff that really doesn’t fit within your investment plan hopefully whatever’s left over is just what will work for you and that you can kind of stick with and avoid all the other pitfalls that a lot of investors fall into.”
Easy fix: Learn more about why an IPS is the secret weapon your retirement plan needs.
5. You Don’t Know What You Don’t Know About Personal Finance
Everyone — rich or poor and young or old — knows less about personal finance than they need to know.
A recent survey suggests that financial literacy is lower than even most people might expect.
Fidelity asked more than 2000 people — half who were between the ages of 55 and 65 and not retired — questions in eight different retirement categories. The average that people got right was a mere 30 percent. Absolutely nobody got all the questions correct and the highest overall grade was 79 percent.
Can you do better than average? (See Fidelity’s guide to retirement IQ.)
Easy fix: Most articles would tell you to hire a financial advisor. However, many people don’t trust advisors — largely because it is impossible to assess whether you are getting good advice or not if you don’t have a good base of financial knowledge.
Perhaps a better way to at least start learning about personal finance is to take stock of your own situation.
6. You Aren’t Saving Enough
According to a 2018 Stanford Center for Longevity report, 30% of baby boomers haven’t saved anything for retirement, and those who have something saved haven’t saved enough.
The median balance for those born between 1948 and 1953 is $290,000. For those born between 1954 and 1959, they had saved around $209,000. That is probably only about half of what the average household needs. (Though, not everyone is average.)
An earlier study from the Insured Retirement Institute (IRI) found that a full 68% of Boomers who lack confidence in their retirement plans wish that they would have saved more, and 67% wish that they had started saving earlier.
Easy fix:
- Do you own your home? If so, have you factored in how your home equity can subsidize your retirement finances either now or at some point in the future?
- Still feeling pretty good? Working a little longer — either part or full time — can dramatically improve your long-term finances.
- Can you delay the start of Social Security to boost your monthly benefit?
- Do you know what is important to you? If you focus on priorities, cutting expenses doesn’t have to feel like a burden.
7. You Don’t Have a Plan for Turning Savings into Income
You have spent your whole life working and saving money — paying down your mortgage and putting some away for retirement.
Retirement is the time to spend it. This is a huge perspective shift and something that people find problematic. Figuring out an efficient way to spend your money while making sure that you don’t run out can indeed be tricky.
Easy fix: You need to develop retirement income strategies. Explore ideas for lifetime wealth and peace of mind, including ways to guarantee your income.
8. You Own Too Much Stuff
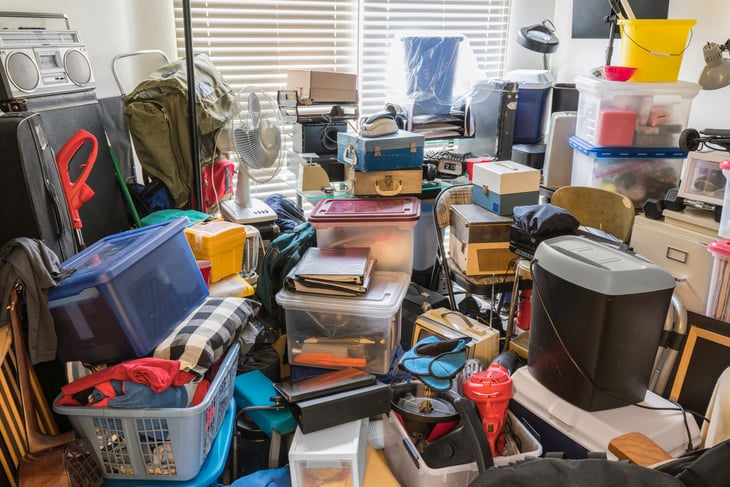
You probably have too much stuff. Don’t believe me? Consider this:
- According to professional organizer Regina Lark, the average U.S. household has 300,000 things.
- A widely reported study from the U.S. Department of Energy reports that of the houses with two-car garages, 25% don’t have room to park cars inside them and 32% only have room for one vehicle.
- The Wall Street Journal reports that Americans spend $1.2 trillion annually on nonessential goods — stuff they do not need.
Easy fix: Retirement is an excellent time to simplify your life and take stock of what you really need and want. Maybe you could even sell some of your unused treasures with the proceeds going toward retirement savings or a fun experience.
And don’t get your heart set on gifting your treasures to your children. Many recent articles indicate that they don’t want it.
9. You Are Paying for Storage
Still don’t believe that too many Americans have too much stuff?
According to self-storage industry statistics, nearly one out of every 3 Americans (33%) rents off-site storage. Are you paying to store stuff you don’t use?
Easy fix: If you have a storage unit, seriously consider whether or not it is a necessity in your life. Clearing it out will take an afternoon, a weekend or even a month or two, but getting rid of this burden could be well worth the short-term hassle.
Here is how one person tackled clearing out their storage unit.
10. You Are Paying for College but Can’t Afford Retirement
According to a survey by T. Rowe Price, about 53% of parents surveyed felt that it was more important to help their child pay for college than to save for their personal retirement. And 68% of participants said that they would be willing to delay retirement to fund college.
Easy fix: Take a moment to think clearly about the future. Not saving (or spending your retirement savings) now will have a profound impact on both you and your children. Consider the following:
- Are your children going to be able to take care of you in the future the way you are taking care of them now?
- Do they want that responsibility as you age?
- Do you want to give up your own autonomy and be beholden to them?
11. You Sacrifice Your Livelihood to Care for Aging Parents
According to the Caregiving Action Network, more than 65 million people, 29% of the U.S. population, provide care for a chronically ill, disabled, or aged family member or friend during any given year and spend an average of 20 hours per week providing care for their loved one.
Caring for your aging parents can be a labor of love. In fact, many people find it to be one of the most rewarding experiences of their lives.
However, it is important to acknowledge the financial costs of caregiving. There is the lack of income, but also a lack of savings for retirement during that time, and also a potential reduction in Social Security income because you are not accumulating credits when you are not working.
Easy fix: Actually, there is no easy fix here. However, a few things you should do before you take on a caretaking role:
- Actively consider how you or you and your spouse can make up for financial losses.
- Get a really good handle on your current and future finances and assess how caretaking will impact your future.
- Evaluate your parents’ finances. Can they compensate you financially? Is there a better financial solution for their care?
- Would merging households be a viable option to generate liquidity from the sale of a home to help fund caregiving and reduce costs?
12. Taking Social Security Too Early
According to a report by the Center for Retirement Research at Boston College, 90% of Americans begin Social Security retirement benefits at or before their full retirement age. In fact, the most popular age to start is 62, the earliest age possible.
Guaranteed retirement income — income that you will receive every month no matter what and for as long as you live — can be the key to a secure retirement. Social Security is one of the best sources of guaranteed retirement income. This is why maximizing your Social Security income is a good move.
Easy fix: If you have not yet started your Social Security, the best thing you can do to live more comfortably in retirement is to wait to claim your benefits. If you have reached full retirement age — which is 66 or 67 depending on when you were born — you can access 100% of your benefits.
13. You Have Too Much Debt

If you don’t have debt, you are in the minority. The average American household debt load, including mortgage, is $101,915, and it is estimated that 77% of American households have at least some type of debt.
Easy fix: Here are 13 tips for dealing with debt.

14. You Hold Too Much Cash
Of all the tactics you can use to achieve a secure retirement, one of the easiest things you can do is to invest your money and earn returns on that investment. Doing this requires virtually no sacrifice, compromise, or a lot of work.
However, a study from BlackRock found that Americans hold 58% of their investable assets in cash, where little or no interest is earned.
Easy fix: Get out of cash and into some kind of holding that can earn interest or dividends. Learn more about the best asset allocation for retirement.
15. You Don’t Have an Emergency Plan
In addition to saving for college and retirement and just paying the bills, you should also always have an emergency fund.
Before you retire, experts recommend that you have the equivalent of 6 months of income saved and available. When you are retired, you may want even more since you may be living off withdrawals and need to protect your money from ups and downs in the financial markets.
However, The Atlantic uncovered shocking analysis from a study by the Federal Reserve Board. They found that nearly half of all Americans – many in the middle class – would have trouble coming up with just $400 to pay for an emergency.
Easy fix: Set aside an amount of money to be used for emergencies. Be sure to replenish these funds when used up.
16. Not Planning for Medical Costs

Medicare does not cover all of your medical expenses, not by a long shot.
According to recent data from Fidelity, a 65-year-old individual retiring today may need $172,500 in after-tax savings to cover health care expenses in retirement — not including long-term care costs. Healthcare is the second biggest retirement expense after housing.
Easy fix:
- Include healthcare costs in your planning.
- Consider healthcare costs if you plan on retiring before Medicare eligibility at age 65.
- Engage in regular exercise and follow a healthy diet to keep the pounds off and keep your blood pressure at a lower level. Cutting out alcohol and cigarettes can also help you avoid possible medical conditions and expenses in the future.
- Reevaluate your supplemental Medicare coverage each year to make sure you have the best plan for your current condition.
17. Not Having a Long-Term Care Plan

Dementia. Stroke. Alzheimer’s disease. The prevalence of these health events is a big reason why you need to make planning for long-term care an important part of your retirement plans.
While about 70% of Americans who get to age 65 will need some type of long-term care, many Americans are unprepared for this reality.
Easy fix: Develop a plan. Insurance is only one option for funding long-term care.
18. You Don’t Think About Minimizing Taxes
While taxes may be less of a factor after retirement than before, they can still add up to hundreds of thousands of dollars over your remaining lifetime.
Easy fix: Explore tips for keeping more of your own money and minimizing taxes after retirement.
19. You Are Stuck in a Rut and Think You Can’t Get Ahead
If you are stressed about money or how to fund retirement, you might just need to change how you think about the problem and what you are doing.
Flipping your perspective enables you to see things in a new and different way. This fresh approach can change your attitude and help spark creative ways of approaching a problem — even a problem like how to retire.
Easy fix: Here are 8 ways to flip your retirement perspective.
20. You Aren’t Sure What You Are Going to Do in Retirement
Do you want to hear something kind of depressing?
Adults aged 65 and older spend threefold more waking time watching TV than young adults. And, what is worse, they enjoy it less. In the American Time Use Survey, TV watching accounted for 25%–30% of waking time and half of leisure activity among adults aged 65 years and older.
Sure, we may be in the golden age of television, but that doesn’t mean that it is the best way to spend your golden years.
It is critically important that you retire to something interesting and engaging and not just retire away from your job. Knowing what you want to do in retirement is critical to maintaining your mental, cognitive and physical health.
Easy fix: Make sure you have a plan for what to do in retirement. Not sure? Explore these resources:
21. Underestimating Your Life Expectancy
It is not adequate to assume that you only need enough retirement assets to sustain your lifestyle through the age of 75, 85, or even older. The fact of the matter is, you have no idea how long you are going to live.
Statistics suggest that there is a greater than 50 percent chance that at least one partner from a couple in their 60s will live to the age of 95.
Does your retirement plan enable you to live till 95? Will you outlive your assets?
Easy fix: Use a life expectancy calculator to help make a more educated guess as to your longevity
22. You Pay Too Much for Financial Guidance
For some, paying for financial guidance is well worth the cost … especially if you are paying an hourly rate for the advice. However, most financial advisors charge a fee based on how much money they manage for you.
That assets under management (AUM) fee typically ranges from 0.25% to 1% or more per year. So, if they are managing $500,000, you are paying them between $1,250 (.25%) and $5,000 (1%) every year.
This fee is often paid for them to actively manage your investments. Sometimes you also get comprehensive planning guidance.
Easy fix: The Boldin Retirement Planner enables you to create a comprehensive financial plan similar to (and in some cases better than) what you can get from an advisor. And you can hire a low-cost coach to help you make sure your information is entered correctly into the plan.
If you think you need more hands-on support, but don’t want to pay AUM fees, you might be interested in guidance from a fee-only advisor. Fee-only advisors charge an hourly or flat fee for advice. However, you typically take action on that guidance by yourself.
23. Failing to Protect Yourself from Financial Fraud

Financial fraud against people 50 and older is a growing concern. Older Americans lost $1.6 billion in 2018 due to financial fraud, and the average victim lost $1,023 according to the FTC.
And researchers have discovered that as we get older, core financial skills can become diminished. Researchers call this age-related financial vulnerability. Our cognitive abilities change in a way that can negatively impact our capacity to make good financial decisions. Becoming a victim of fraud as a result of a decline in these capacities is of particular concern.
Easy fix: Here are ways to protect and prepare yourself from declining financial capacity.
24. Making Emotional Financial Decisions

Emotions can be a double-edged sword in financial decision-making. Unbridled optimism can lead to reckless investments, while fear can trigger hasty withdrawals or risk aversion, hindering individuals from seizing beneficial opportunities.
Emotional choices often undermine rational, long-term financial strategies, leading to impulsive actions that may result in financial setbacks and missed gains. Balancing the useful aspects of emotions with their potential harm in financial decisions is a constant challenge for investors and savers.
Easy fix: It can be useful to gain an understanding of behavioral finance in order to use emotion effectively when it comes to money. Explore brain tricks to help you make better financial decisions.
25. Missing Out on the Tax Benefits of an HSA
Health savings accounts (HSAs) are a powerful savings vehicle due to their unique combination of tax benefits, investment potential, and flexibility. Contributions to HSAs are tax-deductible or pre-tax, and the funds grow tax-free, allowing for significant long-term savings.
Unlike other healthcare accounts, HSA funds roll over from year to year, providing an opportunity for compounding growth. Furthermore, the ability to invest HSA funds in various financial instruments can amplify their potential over time.
HSAs offer financial versatility, allowing for the payment of qualified medical expenses or serving as a retirement savings tool after age 65.
This adaptability, along with the absence of income limits, makes HSAs accessible and invaluable for individuals looking to secure their financial future while simultaneously addressing healthcare needs.
Easy fix: See if you qualify to fund an HSA.
26. Retiring Too Early … or Too Late

Retiring too early or too late both come with their own set of challenges and potential drawbacks.
Retiring prematurely, while offering the benefit of more leisure time, can strain financial resources if one hasn’t adequately saved or planned for a longer retirement. This may lead to financial stress, reduced quality of life, and even a need to re-enter the workforce.
On the other hand, retiring too late, beyond the point of personal well-being or enjoyment, can result in missed opportunities to pursue one’s passions, travel, or spend quality time with loved ones.
Easy fix: Develop a detailed retirement plan to help you gain confidence that you will retire at just the right time.
27. Spending Too Much (or Too Little) in Early Retirement
When people come into a large sum of money, it is tempting to feel wealthier. As a result, some people end up overspending during the first few years of retirement.
Having access to your retirement savings can be dangerous. The temptation to spend can be like the temptation to have a big slice of the chocolate cake that was left out on the counter.
Easy fix: Conventional wisdom is that you should only withdraw about 4% of your nest egg to live on per year. But even that has come into question lately in the low-interest-rate environment that we are in.
The best retirement solution is to be extremely careful with your retirement planning. Set goals for what you want to do, and budget accordingly. It can be okay to spend more when you retire, just make sure that you put that into your retirement plan.
Some retirement calculators let you set different spending levels for different times during retirement. This is a great way to see if you can afford the splurge or not.
28. You Don’t Have a Written Retirement Plan
Only 30% of Americans have a long-term financial plan that includes savings and investment goals.
Furthermore, Americans tend to spend more time on research about vacation than they do on retirement planning, even though retirement planning needs to be an ongoing activity.
When you retire, you are no longer living month to month or year to year. When you stop working, you are dealing with a finite set of financial resources that need to be budgeted to fund the rest of your life. You really do need a plan.
Easy fix: Assess what you have and what you need for retirement. Find ways to improve your situation. Do it right now.
29. You Aren’t Prioritizing Your Time
Your time (not money) is your most finite and precious resource. If you don’t actively align your days with what matters most — relationships, creativity, learning, giving back, health — you risk letting retirement slip away without fulfillment.
Easy fix:
Define your “life priorities” list: Sit down (with your partner, if applicable) and list three to five domains that matter most (e.g. family, creativity, mentoring, travel, community, health). Give each domain a one-sentence vision of what “great” looks like for you in that area.
Do a “time audit” for 2 weeks: Track how many hours you spend in different buckets:
- Essential (sleep, meals, chores)
- Obligations (appointments, errands)
- Low value (screen time, distractions)
- Aspirational (time spent on your priority domains)
Notice the gaps between your ideal vision and what actually happens.
Schedule your priorities first, then fill around them: Block time in advance on your calendar for the most important domains (e.g., morning for writing; afternoons for relationships, exercise, volunteering). Protect those blocks from low-value intrusions. If something doesn’t fit, resist it.

Add a Comment