


The urge to splurge strikes everyone, but impulse buys add up fast—Americans spend an average of $314 a month on unplanned purchases.
That’s nearly $4,000 a year that could be growing in your retirement account instead. These simple psychological tricks can help you regain control without relying solely on willpower.
Setting up a high-yield savings account specifically for impulse spending creates instant awareness of what each spontaneous purchase is really costing you.
Pro Tip: Earn as much as possible on your emergency savings. For example, SoFi Checking is offering 3.8% interest, plus a potential $300 signup bonus. (May change without notice.)
1. The cash freeze technique
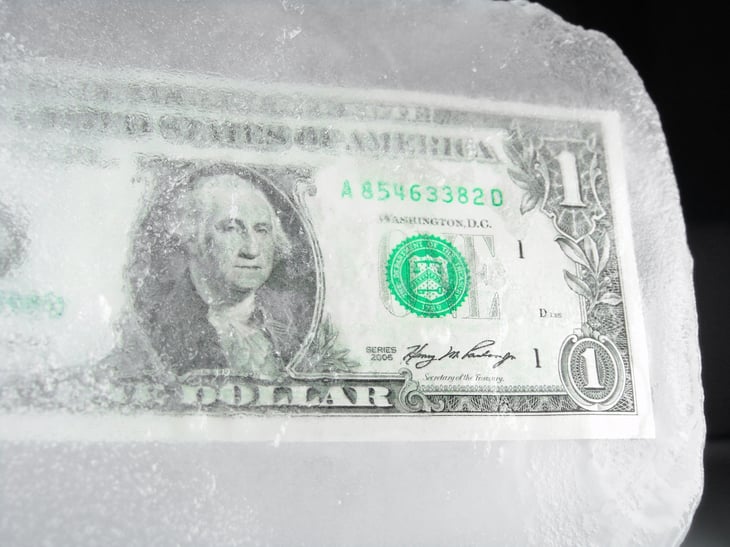
Literally freeze your credit cards in a block of ice. This bizarre but effective method creates a physical barrier between you and impulsive purchases. When temptation strikes, you’ll need to wait for the ice to melt – typically long enough for the spending urge to pass.
This technique works by introducing what behavioral economists call “friction” into your spending process.
Unlike digital payments which are designed for frictionless transactions, the frozen card method forces you to consider if the purchase is truly worth the wait. For essential purchases, consider using cards with favorable terms.
Pro Tip: Boost your shopping power: Get 0% intro APR for purchases and balance transfers for 15 months. Plus, earn a bonus of 20,000 miles once you spend $500 on purchases within 3 months from account opening.
2. Shop with monopoly money first

Before making a non-essential purchase, visualize the cost in Monopoly money or another tangible form like hours worked.
Lay out actual Monopoly bills equaling the amount before buying online—this creates psychological distance from digital money.
Studies show we spend up to 100% more with credit cards because digital transactions don’t activate the same pain receptors as cash. Identifying and addressing your personal spending triggers can significantly boost your financial health.
Pro Tip: Need cash, debt relief, or help funding a major expense? Find the best options tailored to your needs—fast, easy, and secure. Explore financial solutions here.
3. The mirror neuron trick

Place a small mirror near your computer when shopping online or carry one while shopping in stores. Seeing your reflection activates self-awareness circuits and makes you more likely to align purchases with long-term goals.
One study found people were 30% less likely to make impulse buys when they could see themselves. This mirror trick taps into your brain’s mirror neurons—just like external accountability from a financial professional can support lasting discipline.
Pro Tip: If you’ve got at least $100,000 in investments, check out a free service called SmartAsset. You fill out a short questionnaire and instantly get matched with up to three vetted financial advisors in your area.
4. The 10-10-10 rule

Before any purchase, ask yourself three questions: How will I feel about this purchase in 10 minutes? In 10 months? In 10 years? This mental time travel exercise helps distinguish between momentary desires and lasting value.
The technique works by activating your brain’s prefrontal cortex, responsible for long-term planning. Most impulse purchases fail the 10-year test, revealing them as fleeting wants rather than genuine needs or meaningful investments.
This same long-term thinking is crucial for retirement planning—where your future self will thank you for the discipline you show today.
Pro Tip: Start your retirement savings today with matched contributions and let your money grow. Sign up for a SoFi IRA to take advantage of compounding interest and retire comfortably. The longer you wait, the less you’ll earn. Get started today.
5. Practice financial fasting
Designate one day each week as a zero-spending day where you commit to purchasing absolutely nothing, not even a coffee or snack. Mark these days on your calendar and treat them as non-negotiable appointments with your financial health.
Financial fasting works by breaking unconscious spending patterns and increasing awareness of habitual purchases. Many practitioners report that after several weeks, they naturally become more deliberate shoppers on non-fasting days as well.
For those struggling with significant debt, these small daily habits can be part of a larger debt management strategy.
Pro Tip: If you have more than $20,000 in unsecured debt, get some professional help. National Debt Relief is a trusted source for free advice and assistance.
6. The stranger test

Before finalizing a purchase, imagine explaining it to a stranger who asks, “Why did you buy that?” If you feel defensive or can’t justify it confidently, it’s likely an impulse.
This technique taps into your brain’s social accountability circuits, activating areas that support rational decision-making over impulsive urges. The same principle applies to investing—each choice should withstand scrutiny.
Pro Tip: One modern way to diversify is with real estate and venture capital. Companies like Fundrise, offer investments as small as $10.
7. Create a purchase parking lot
Instead of buying items immediately, add them to a digital or physical “purchase parking lot” with a mandatory 72-hour waiting period. Research shows that simply delaying a purchase by three days can reduce impulse buying by over 50%.
This method works because it separates the discovery dopamine hit from the acquisition dopamine hit. After 72 hours, you can evaluate the purchase with your rational brain rather than your emotional brain.
Keep track of how many items you ultimately decide against buying to visualize your savings. During your waiting period, consider productive ways to earn instead of spend.
Pro Tip: Earn up to $1000 per month doing simple tasks with KashKick!
8. The purpose password technique

Change your online shopping passwords to financial goals like “Save4Retirement2025!” or “NoDebt2024.” This forces you to type your financial priorities before each purchase, creating a powerful pattern interrupt.
This technique combines psychological priming with a physical action, making your financial goals salient at precisely the moment you’re about to spend.
The brief keyboard action creates just enough pause for your prefrontal cortex to activate and potentially override the impulse. Your passwords protect your accounts—but proper estate planning protects your entire financial legacy.
Pro Tip: Want to save time, money, and stress while protecting your family? Where there's a will, there's a way.
9. Harness the power of disgust
Create a strong mental link between unnecessary spending and something you find disgusting. Some financial therapists recommend using a repulsive image—like moldy food—as your phone wallpaper or near your credit cards.
This taps into the amygdala, where disgust can override the pleasure tied to impulse buying. It may seem extreme, but it works because disgust is such a powerful emotional response.
Similarly, the fear of leaving loved ones unprotected can also be a strong motivator.
Pro Tip: Life insurance is a must to protect your family. Here's a place to get a free, no-obligation quote.
Your financial freedom toolkit

These unconventional hacks work because they bypass willpower – which is finite and unreliable – and instead rewire your brain’s response to spending triggers. Start with just one technique that resonates with you. After it becomes habitual, add another.
The typical impulse shopper who implements even three of these strategies can save between $2,000-$5,000 annually – enough to meaningfully impact your retirement readiness or eliminate debt years sooner.
While controlling impulse spending helps build wealth in the short term, diversifying your investments protects that wealth for the long term, particularly during economic uncertainty.
Pro Tip: Protect your wealth with an asset that can hedge against the damaging effects of a recession and financial calamity by opening a gold IRA.

Add a Comment