


As policies shift under the current administration, Americans increasingly need to become their own financial defenders. The Consumer Financial Protection Bureau (CFPB), created after the Great Recession to safeguard consumers, is significantly weakened.
This regulatory retreat means you must take proactive steps to guard your money. These nine strategies can help fortify your finances against potential threats in this changing landscape.
With so many changes happening to financial regulations, many people find that professional guidance helps them navigate these uncertain waters more confidently.
Pro Tip: If you’ve got at least $100,000 in investments, check out a free service called SmartAsset. You fill out a short questionnaire and instantly get matched with up to three vetted financial advisors in your area.
1. Speak up without apology

Many consumers hesitate to question financial terms or charges out of embarrassment or fear of appearing confrontational. Remember that asking for clarification is your right, not an imposition.
When transacting purchases, practice straightforward phrases like “Could you explain this fee?” or “What alternative options might work better for my situation?” Financial professionals expect these questions, and the most reputable ones welcome them.
Finding the right financial solutions starts with asking the right questions, whether you’re talking to a bank, lender, or other financial service provider.
Pro Tip: Need cash, debt relief, or help funding a major expense? Find the best options tailored to your needs, fast, easy, and secure. Explore financial solutions here.
2. Document everything
In financial disputes, detailed records often determine the outcome. Develop a system for preserving evidence of all significant financial interactions, take screenshots of online transactions, save email confirmations, and record the date, time, and name of all representatives during phone conversations.
These records become invaluable if you need to contest charges or prove your case to regulators. This same documentation principle applies to all important life matters, including planning how your assets will be distributed.
Pro Tip: Want to save time, money, and stress while protecting your family? Where there's a will, there's a way.
3. Create a digital alert system

Financial institutions offer notification services that can serve as your personal security team. Configure text and email alerts for all your accounts — banking, credit cards, investment platforms, and payment apps.
Set notifications for any transaction or establish thresholds (like purchases over $100) to flag potential unauthorized activity. This early warning system helps you spot problems immediately rather than discovering them weeks later when reviewing statements.
This same vigilance should extend to your recurring expenses like insurance premiums. Just as you monitor transactions to catch fraud, regularly compare major expenses like car insurance rates to catch unnecessary spending.
Many drivers are overpaying simply because they haven’t compared options recently.
Pro Tip: Save up to $600 on your car insurance with this car insurance comparison site.
4. Conduct a subscription audit
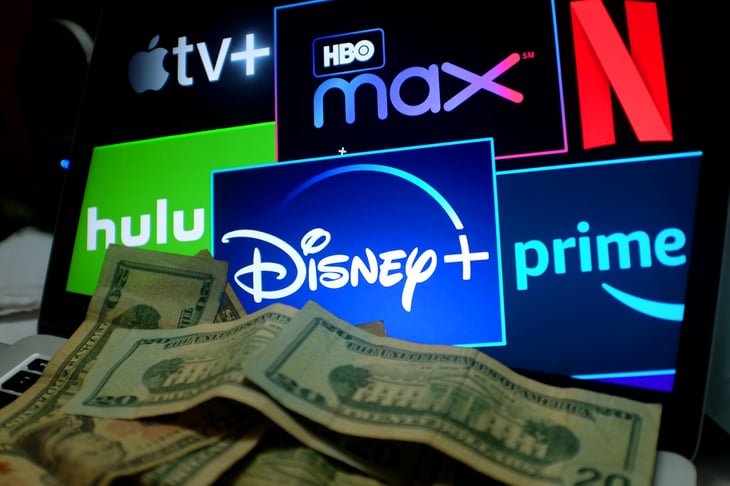
Recurring charges have become a revenue lifeline for companies across industries. Review a full year of bank and credit card statements to identify all subscription services.
Make deliberate decisions about which ones provide genuine value versus those draining your finances through inertia. Create calendar reminders to reevaluate these services annually, as companies frequently increase prices after your initial sign-up period.
When auditing your regular payments, don’t overlook interest charges on credit card balances, which can be as costly as unnecessary subscriptions.
Pro Tip: Boost your shopping power: Get 0% intro APR for purchases and balance transfers for 15 months Plus, earn a bonus of 20,000 miles once you spend $500 on purchases within 3 months from account opening.
5. Eliminate costly overdraft services
Banks generate billions in revenue from overdraft fees, costing around $29 per incident. Contact your financial institution to opt out of overdraft “protection” on your debit card and ATM transactions.
While this means your card may be declined if you lack sufficient funds, it prevents the cascade of expensive fees that often accompany overdrafts. Consider linking a savings account as a cheaper backup funding source.
If overdraft fees are already causing financial strain, you might face larger debt challenges requiring more comprehensive solutions.
Pro Tip: If you have more than $20,000 in unsecured debt, get some professional help. National Debt Relief is a trusted source for free advice and assistance.
6. Lock down your credit files
Credit bureaus maintain detailed records of your financial history that lenders use to evaluate you. Prevent unauthorized access by freezing your credit reports with all three major agencies – Equifax, Experian, and TransUnion. This free service prevents anyone from opening new accounts in your name without your permission.
When you need to apply for credit, you can temporarily lift the freeze with a PIN you create during the process. While protecting your credit prevents unauthorized access, there are times when you might need to leverage your home’s equity responsibly.
Pro Tip: A home equity loan is a great way to access fast cash. Take a minute right now and see how much you can get, how fast you can get it and how little you'll pay.
7. Question your banking relationship

The average American maintains the same checking account for nearly two decades, potentially missing better options, according to a Bankrate survey. Schedule an annual financial checkup to evaluate whether your current banking arrangement still serves your needs.
Ask directly about available higher-interest accounts, fee-free services, or relationship benefits you might qualify for. Financial institutions rarely volunteer this information without prompting.
With interest rates higher than they’ve been in years, many people are losing significant money by sticking with low-yield accounts.
Pro Tip: Earn as much as possible on your emergency savings. For example, SoFi Checking is offering 3.8% interest, plus a potential $300 signup bonus. (May change without notice.)
8. Recognize government impersonation tactics

Scammers frequently masquerade as tax authorities, especially during filing season. The IRS rarely calls you directly as their first contact method — they start with official letters.
Be immediately suspicious of any caller claiming to be from a government agency who demands payment through gift cards, cryptocurrency, wire transfers, or prepaid debit cards.
These payment methods are red flags for fraud since they cannot be traced or recovered. If you have legitimate tax issues, professional assistance can help resolve them properly.
Pro Tip: Struggling with tax debt? Need cash, debt relief, or help funding a major expense? Find the best options tailored to your needs—fast, easy, and secure. Explore financial solutions here.
9. Filter unwanted communications

Modern scammers use sophisticated techniques across multiple channels to separate you from your money. Configure your smartphone to automatically screen calls from unknown numbers, sending them straight to voicemail.
Similarly, email filtering tools can be used to quarantine suspicious messages. Remember that legitimate financial institutions rarely initiate urgent contact through calls, texts or emails — they typically send formal letters for essential matters.
As you screen for financial threats, being proactive about screening for health risks is another form of self-protection.
Pro Tip: Life Line Screening reveals hidden risks so you can act early. Book a screening today and have peace of mind.
Your financial self-defense toolkit

With regulatory protections in flux, your vigilance becomes your strongest asset. These nine strategies create multiple layers of protection against the most common financial threats.
By consistently implementing them, you establish a personal security system that works regardless of changing political winds or regulatory priorities.
The best defense against financial harm isn’t waiting for government intervention – it’s your own informed, systematic approach to managing your money. This includes diversifying your investments to protect against economic uncertainty.
Pro Tip: Protect your wealth with an asset that can hedge against the damaging effects of a recession and financial calamity. If you’re over 50 and curious about investing in Gold, now is a great time to get your FREE 2025 Gold Information Kit and protect your future with physical precious metals!

Add a Comment