


The IRS doesn’t like when you take money out of your retirement accounts before retirement, and it normally dishes out a financial punishment for doing so.
In the case of an individual retirement account (IRA), early withdrawals before age 59½ are “subject to being included in gross income plus a 10 percent additional tax penalty,” the IRS says. The same is true if you take a loan from your 401(k) and fail to pay it back.
But in some particular life situations, you can safely use retirement funds for other purposes. Following are several situations in which you can withdraw retirement money early without paying a federal tax penalty.
A word of caution
While the following situations won’t trigger an IRS penalty, that doesn’t mean they won’t cost you. You will still have to pay income tax on any money taken from a traditional retirement account.
Plus, you’re borrowing against your future. Even if you pay it all back, the opportunity cost could be enormous. All the money you withdraw will miss out on potential gains. A stock rally might have quickly grown into a massive profit and could have compounded into even more over the years between now and retirement.
The following situations are serious enough to justify leeway from the IRS so there’s nothing wrong with using money if you need to. But it’s best to avoid withdrawing money early whenever possible.
1. People experiencing a financial emergency
Types of plan this penalty exception applies to: Qualified plans like 401(k)s, IRAs, certain pensions
Maximum withdrawal amount allowed: $1,000 per year
The Secure 2.0 Act of 2022 enabled those with retirement accounts to withdraw money “for purposes of meeting unforeseeable or immediate financial needs relating to necessary personal or family emergency expenses.”
You don’t particularly need to offer justification either — you only must provide “written certification” that you need the money. You can also repay it within three years.
This provision of the law took effect in 2024.
2. Domestic abuse victims
Types of plan this penalty exception applies to: Qualified plans like 401(k)s, IRAs, certain pensions
Maximum withdrawal amount allowed: $10,000 or half of the retirement account, whichever is less
Another change brought by the Secure 2.0 Act allows recent victims of domestic abuse to withdraw retirement money. The abuse must have happened in the past year, and the money can be repaid within three years. If repayment is made, any income tax paid on the withdrawal will be refunded.
To qualify for this exception, you must self-certify that you fit the law’s definition of domestic abuse: “physical, psychological, sexual, emotional, or economic abuse, including efforts to control, isolate, humiliate, or intimidate the victim, or to undermine the victim’s ability to reason independently, including by means of abuse of the victim’s child or another family member living in the household.”
Like the exception for emergency expenses, this exception took effect in 2024.

3. First-time homebuyers
Types of plan this penalty exception applies to: IRAs
Maximum withdrawal amount allowed: $10,000
Under Internal Revenue Code section 72(t)(2)(F), qualified first-time homebuyers can withdraw up to $10,000 to support that purchase, whether they are buying or building the property. If your spouse qualifies, they can also withdraw $10,000 for the same purpose.
4. Disabled people
Types of plan this penalty exception applies to: Qualified plans like 401(k)s, IRAs, certain pensions
Maximum withdrawal amount allowed: N/A
If you become permanently and completely disabled, there is no penalty on early withdrawals from your retirement accounts.
Under the rules, you must prove “that you can’t do any substantial gainful activity because of your physical or mental condition,” and a physician must attest your condition “can be expected to result in death or to be of long, continued, and indefinite duration.”
5. Natural disaster victims
Types of plan this penalty exception applies to: Qualified plans like 401(k)s, IRAs, certain pensions
Maximum withdrawal amount allowed: $22,000
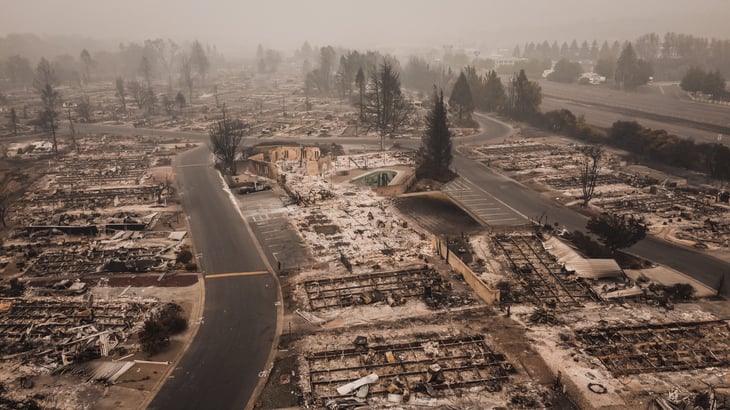
If your home is in the area of a federally declared disaster, and you have some economic loss because of it, you can withdraw money early from a retirement account without paying the 10% penalty. The rules note:
Qualified disaster distributions are permitted without regard to your need or the actual amount of your economic loss. Examples of an economic loss include, but aren’t limited to:
- Loss, damage to, or destruction of real or personal property from fire, flooding, looting, vandalism, theft, wind, or other cause;
- Loss related to displacement from your home; or
- Loss of livelihood due to temporary or permanent layoffs.
6. College students and their relatives
Types of plan this penalty exception applies to: IRAs
Maximum withdrawal amount allowed: Up to the paid cost of qualified higher education expenses
You can withdraw retirement money to pay the tuition, fees and cost of books and supplies for college courses taken by you, your spouse, your children or grandchildren. Room and board also qualifies for people who are students at least half-time.
7. New parents
Types of plan this penalty exception applies to: Qualified plans like 401(k)s, IRAs, certain pensions
Maximum withdrawal amount allowed: $5,000 per child
Whether through birth or adoption, within a year of adding a child to your family, you may withdraw up to $5,000 from your retirement account without paying a 10% early withdrawal penalty. You can repay this money later. In the case of adoptions, the child must be under the age of 18 or incapable of supporting themselves.
8. Unemployed people
Types of plan this penalty exception applies to: IRAs
Maximum withdrawal amount allowed: Up to the cost of health insurance
If you become unemployed and receive unemployment benefits for 12 weeks in a row or longer, you can withdraw money to pay for personal or family health insurance. You can do this up to two months after getting a new job, but only during the year you get unemployment benefits or the following year.

Add a Comment