


Buying a home is often seen as a major milestone in finances and in life. However, even after you buy a home, you might be surprised to discover that it’s not as affordable as you thought.
Zillow estimates that the average annual hidden cost of homeownership is $15,979 in the United States.
Here’s what you need to know about several common, but often overlooked, homeowner costs before buying property — and how to keep them from breaking the bank after you become a homeowner.
1. Utility bills
Homeowners can expect to pay an average of $401 a month for utilities, according to Move.org. And that doesn’t include such things as trash collection, phone, internet and streaming services.
There are substantial steps you can take to lower your utility bills, though. They include:
- Making sure your home is properly insulated.
- Reducing your use of electricity and water.
- Using smart appliances and programmable thermostats.
Just upgrading to smart power strips can save you money.
2. Homeowners insurance
People get caught up in buying their dream home and forget to consider the cost of insuring it, says Casey Fleming, a veteran of the California mortgage industry and author of “The Loan Guide: How to Get the Best Possible Mortgage.”
“Homeowners insurance is a bill most people pay twice a year, and it can add hundreds of dollars to your home costs,” Fleming tells Money Talks News.
The annual cost of insuring your home averages $2,003, according to Zillow.
Fleming recommends shopping around once a year to see if you can get a better deal on homeowners insurance. You can use online tools like this one from FinanceBuzz to quickly and easily compare rates with just a few clicks.
3. Catastrophic insurance
In some areas, it’s not enough to just get homeowners insurance. If you live in a state prone to natural disasters, you might need to purchase separate policies to cover your home in case of a hurricane, tornado or earthquake.
Other than shopping around, there’s little you can do to reduce the cost of insurance for natural disasters.
In some cases, like in the instance of flood insurance, your only option is the U.S. government’s National Flood Insurance Program. So, you have to consider whether the added cost of such insurance is worth living in a particular location.
4. Property taxes
Most people determine whether they can afford a home based on the monthly mortgage payment, says Mindy Jensen, a real estate agent in Colorado and podcast host for the real estate education website BiggerPockets. But property taxes can add thousands of dollars per year to the cost of homeownership.
Property taxes average $3,030 per year nationwide, according to Zillow. However, in high-cost markets in places such as California and New York, the property tax bill could be more than $1,000 per month, Jensen tells Money Talks News.
“There’s not a lot you can do to reduce your property taxes, other than challenge the assessment,” she explains. “Or move to a state with lower taxes.”
5. HOA fees
The average homeowner association (HOA) fee for a single-family home in $300 per month — $3,600 per year — according to iPropertyManagement.
These fees can cover general maintenance on community buildings or fences in the development and in shared areas such as a park. In some cases, fees can even include trash pickup, snow removal and sewer maintenance, says Fleming.
Before buying a home in a subdivision or development, check into the HOA fees to determine whether you want to pay them.
6. Heating and cooling systems
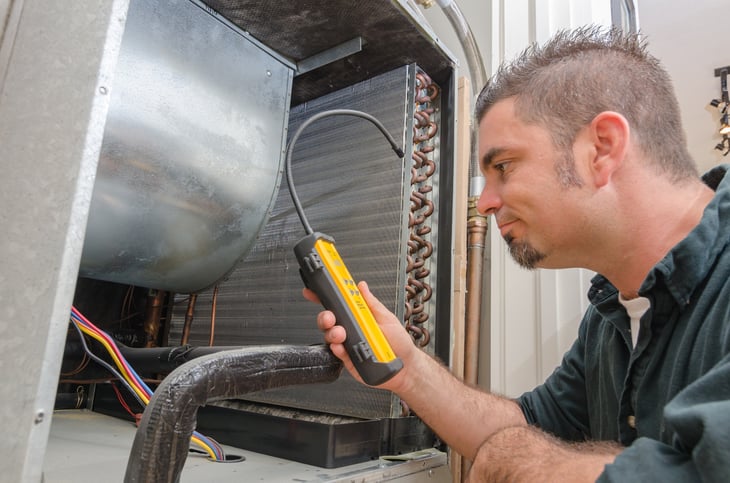
Furnaces, air conditioners and similar systems add to the cost of homeownership in multiple ways.
“You need to perform regular maintenance, and then you need to consider what happens when something breaks,” Jensen says.
Ongoing maintenance — including changing filters and doing annual tune-ups — can save money in the long run by extending the life of your systems.
Jensen recommends setting aside money in a maintenance fund to help keep these costs within your budget.
Additionally, make sure to get a home inspection and have a specialist look at the systems before you buy a home so you don’t end up with a breakdown shortly after moving in.
“If a system is old or could break, a home inspection can be a way for you to get the seller to pay for repairs so you don’t have to,” says Jensen.

7. Time
Many people don’t factor in the cost of their time when owning a home, says Jensen.
“Taking care of a home — from keeping it clean to maintaining and repairing it — can be time-consuming,” she notes. “Decide what your time is worth and whether some things are worth do-it-yourself solutions.”
Beyond the cost of time, homeowners pay an average of $10,946 annually to maintain their home, according to Zillow.
8. Home furnishings
“When you move into a home, you often have to buy things that were provided for you in a rental,” says Fleming. “You’re buying window blinds, shower curtains, furniture for extra rooms and maybe a washer and dryer.”
All of these items start to add up. Check with secondhand shops and compare prices when buying items to outfit your home.
“Be realistic about what you need right now,” says Fleming. “You should probably buy the window treatments immediately, but you might be able to hold off on the extra couch for your downstairs TV room.”
9. Yard maintenance
Lawn care can cost as much as $100 to $200 per month, reports HomeAdvisor, an online marketplace for home services.
Buying the right products to keep your lawn healthy might not be a huge expenditure, but it can add up over time.
Comparing service and product prices and doing ongoing maintenance can help reduce costs. So can using drought-resistant plants or landscaping techniques designed to reduce the need for maintenance in the first place.
10. Replacing locks
You never know who has copies of the key to your new home. So, replacing your outside locks after moving in is a must.
To save money, you can buy new doorknobs and locks at a hardware store and install them yourself. Otherwise, the national average cost to hire a locksmith is roughly $100 to $250, according to HomeAdvisor.

Add a Comment