


Trump’s planned tax policies may benefit your bottom line, particularly if you have a high income.
Think back to the Tax Cuts and Jobs Act (TCJA) of 2017. Championed by former President Donald Trump, it brought sweeping changes to the tax code, impacting millions of Americans. The reform aimed to simplify the system, reduce tax burdens, and incentivize economic growth.
While its effects vary depending on income and circumstances, many taxpayers saw opportunities to lower their tax bills. Understanding these key changes is essential to maximizing potential savings and avoiding leaving money on the table.
With careful planning, these provisions might help you keep more of your hard-earned money.
1. Lower individual tax rates
Trump’s tax reform reduced income tax rates across most brackets. For example, the top rate dropped from 39.6% to 37%, and other brackets saw reductions ranging from 1% to 4%.
These lower rates mean that many taxpayers keep more of their income. For instance, a married couple earning $75,000 might save hundreds of dollars annually under the revised tax rates.
Review your tax bracket and adjust your withholdings if necessary as new tax plans are enacted. Ensuring accurate withholdings can maximize your take-home pay throughout the year while preventing overpayment.
Pro Tip: If you’ve got more than $100,000 in savings, get some advice from a pro. SmartAsset offers a free service that matches you to a vetted, fiduciary advisor in less than 5 minutes.
2. Doubling the Standard Deduction
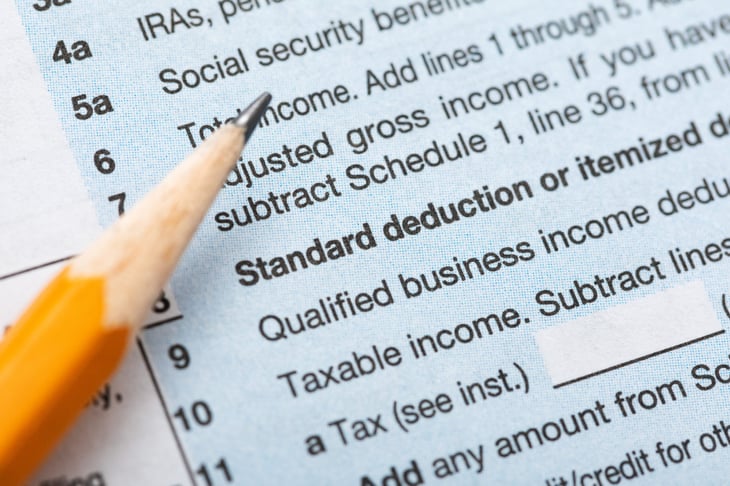
The TCJA nearly doubled the standard deduction, making it more beneficial for many taxpayers. In 2023, the standard deduction was $13,850 for single filers and $27,700 for married couples filing jointly, up from $6,350 to $12,700 pre-reform.
This change simplified tax filing and reduces taxable income for those who don’t itemize deductions. Families and individuals with straightforward financial situations particularly benefited.
If you typically itemized in the past but your deductions no longer exceed the standard amount, this provision ensures you still receive significant tax savings without the hassle of itemizing.
Pro Tip: Gold has been a trusted hedge against uncertainty for centuries. Learn more by visiting here.
3. Expanded Child Tax Credit
Under the tax reform, the child tax credit increased from $1,000 to $2,000 per qualifying child, with $1,400 refundable.
This change directly reduces tax liability and provides substantial relief for families. For example, a family with two children could see up to $4,000 in tax savings. The income phase-out threshold was also raised, allowing more middle—and upper-income families to qualify.
To take advantage of this, ensure your dependents meet the age and eligibility requirements. This enhanced credit can make a meaningful difference in your family’s finances.
Pro Tip: Life insurance is a must to protect your family. Here's a place to get a free, no-obligation quote.
4. Reduction of corporate tax rates
The TCJA slashed the corporate tax rate from 35% to 21%, benefiting small business owners, entrepreneurs, and employees. The reform introduced a 20% Qualified Business Income (QBI) deduction for those running pass-through businesses like LLCs or S corporations.
This deduction can significantly reduce taxable income for eligible businesses, potentially lowering tax bills by thousands. If you’re self-employed or own a small business, consult a tax professional to ensure you optimize your deductions and fully leverage this provision.
Pro Tip: Slash expenses on dining, travel, eyeglasses, prescriptions and more with AARP – Just $12/year with auto-renewal. Join now and save hundreds.
5. Elimination of the individual mandate penalty
The tax reform repealed the Affordable Care Act’s individual mandate penalty, which started in 2019. This penalty previously required uninsured individuals to pay a fine when filing taxes.
Without this penalty, taxpayers without health insurance no longer face additional costs, saving potentially hundreds or thousands annually. While this change reduces financial pressure for those without insurance, it’s still essential to weigh the benefits of health coverage against potential healthcare costs.
Pro Tip: Medicare doesn’t pay for everything. Fill in the gaps with a Medicare Supplement plan to pay what Medicare doesn’t.
Maximizing your tax savings
Trump’s tax reform introduced opportunities for taxpayers to reduce their financial burdens, but understanding how to navigate these changes is crucial.
Lower rates, expanded credits, and increased deductions offer meaningful savings if utilized effectively. Review your tax situation, adjust withholdings, and consult a tax professional if needed. Staying informed about tax law changes ensures you’re positioned to maximize your financial opportunities and keep more money in your pocket.

Add a Comment