


Home insurance is a necessity, but that doesn’t mean you have to overpay. Many homeowners unknowingly leave money on the table by missing out on discounts, skipping cost-saving upgrades, or sticking with the wrong policy.
Now is the time to examine your coverage more closely and explore ways to cut costs while keeping your home protected. From bundling policies to making simple security improvements, small changes can add up to big savings.
In this guide, we’ll walk through the 10 best ways to lower your home insurance bill without sacrificing the protection you need.
1. Increase your deductible

Raising your deductible — the amount you pay out of pocket before insurance kicks in — can lower your premium substantially.
For example, increasing your deductible from $500 to $1,000 could reduce your annual premium by up to 25%. However, ensure the higher deductible is manageable in case of a claim.
This strategy works best for homeowners who can afford minor repairs out of pocket and want to reserve insurance for major incidents.
Take a moment to ensure your family is protected by life insurance if they depend on your earnings.
Pro Tip: Life insurance is essential to ensure your family’s financial security. Here's a place to get a free, no-obligation quote today and provide peace of mind for those who depend on your earnings.
2. Improve home security
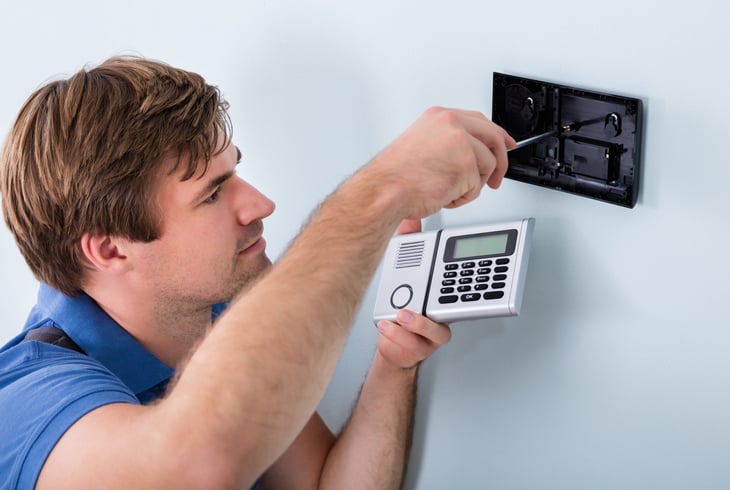
Upgrading your home’s security can significantly reduce your risk of theft, which insurers reward with lower premiums. Installing features like monitored alarm systems, smoke detectors, or deadbolt locks can earn you 5% to 15% discounts.
Some companies offer even greater discounts for advanced systems, like smart home security. Check with your insurer to see which upgrades qualify for savings and invest in measures that align with your budget.
Pro Tip: Need cash, debt relief, or help funding a major expense? Find the best options tailored to your needs—fast, easy, and secure. Explore financial solutions here.
3. Review your coverage annually
Your insurance needs can change over time. For example, paying off your mortgage or making significant home upgrades could affect the coverage you need.
Reviewing your policy annually ensures you’re not paying for unnecessary coverage or missing out on potential discounts. Update your insurer with home or personal circumstances changes to optimize your policy and premiums.
4. Shop around for the best rates
One of the simplest ways to lower your home insurance expenses is to compare quotes from multiple providers.
Rates can vary significantly depending on the insurer, so it pays to do your homework. Use online comparison tools or work with an independent insurance agent to explore your options.
Don’t just focus on cost — ensure the policy covers your needs and that the company has a solid reputation for customer service and claims handling. Regularly re-evaluating your provider can uncover better deals and keep your premiums competitive.
Pro Tip: Don’t overpay for home insurance! Compare quotes from top providers today to ensure you’re getting the best coverage at the right price.
5. Bundle your policies
Many insurance companies offer discounts when you bundle multiple policies, such as home and auto insurance. Bundling can save you anywhere from 5% to 25% on your premiums.
Managing all your policies with one provider simplifies billing and customer service. Before bundling, compare standalone and bundled rates to ensure you’re getting the best deal overall.
Pro Tip: Want to save on car insurance? Use a car insurance shopping site to compare rates and potentially save up to $600 per year.
6. Maintain a good credit score
Many insurers consider credit scores when setting premiums. A strong credit history suggests you’re less likely to file claims, making you a lower-risk policyholder.
Improve your credit by paying bills on time, reducing debt, and correcting errors on your credit report. Regularly monitoring your credit can help you spot issues early and maintain a score that earns you the best insurance rates.
7. Avoid filing small claims
Filing frequent or minor claims can lead to higher premiums over time. Insurance is best used for major incidents, so consider paying for small repairs out of pocket.
Many companies offer claim-free discounts that reward policyholders who go without filing a claim for several years. By avoiding small claims, you preserve these discounts and maintain a clean insurance record.
8. Make your home disaster-resistant
Fortifying your home against natural disasters can reduce your premiums, especially if you live in high-risk areas. Insurers often reward upgrades such as adding storm shutters, reinforcing your roof, or retrofitting for earthquakes.
While some of these improvements require upfront investment, they can pay off in long-term savings and added peace of mind.
9. Take advantage of discounts
Insurance companies often offer discounts that you might not know about. These include senior discounts, loyalty rewards, and savings for using paperless billing.
Ask your insurer for a list of available discounts and ensure you take advantage of all that apply. Even small discounts can add up to significant savings over time.
10. Reduce coverage for unnecessary items
Over-insuring your home or belongings can inflate your premiums. For example, you might be paying to insure high-value items you no longer own.
Conduct a detailed review of your policy to ensure you’re not covering outdated items or unnecessary extras. Adjusting coverage limits to reflect your current needs better can reduce costs without compromising essential protection.
Smart choices for long-term savings
Reducing your home insurance expenses doesn’t mean sacrificing quality coverage.
You can simultaneously protect your home and wallet by taking proactive steps like reviewing your policy, improving your home’s security, and exploring discounts.
Today’s Small adjustments can lead to significant savings, ensuring your home remains safe and secure without overextending your budget.

Add a Comment