


Now that Tax Day is behind you, it’s tempting to forget about it, but that’s exactly how to ensure tax-time panic sets in again next year.
Instead, take stock while it’s still fresh. With a few practical moves, you can reduce your stress, increase your savings, and be in a far better spot when next April rolls around.
Pro Tip: If you’re worried about inflation, market shocks, and financial uncertainty, consider this trusted strategy. Gold can offer a strong defense against economic downturns. Think about safeguarding your savings by opening a gold IRA.
1. Use home equity wisely
If you’re facing unexpected expenses or tight cash flow, consider tapping into your home’s value without taking on monthly debt.
This can be a strategic move to strengthen your financial base.
Pro Tip: You may be one of many Americans who collectively have $30 trillion in untapped home equity, yet most can’t access it without taking on debt. Hometap lets you unlock up to $600K of your wealth without monthly payments or personal liability.
2. Plan ahead for retirement income
Retirement planning can also affect your taxes now and in the future.
If you’re struggling to cover expenses, especially in retirement, here’s one solution worth exploring.
Pro Tip: A reverse mortgage can turn your home equity into tax-free cash for seniors 62+, no house sale required. Use the funds for medical bills, home repairs, or even that dream vacation—without monthly payments!
3. Adjust your withholding now
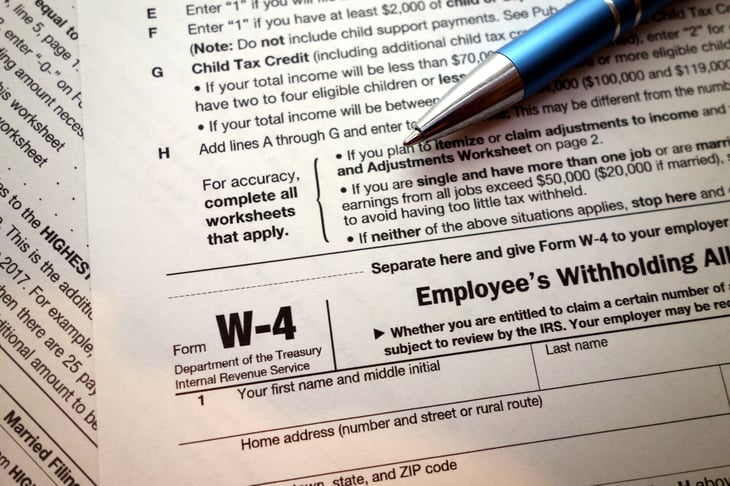
If you owed more than expected or got a surprise refund, your paycheck may need tweaking.
Too little withheld means an ugly tax bill. Too much means giving the government an interest-free loan.
Professional guidance can help strike the right balance.
Pro Tip: If you have over $150,000 in investments, consider talking to a professional financial advisor. WiserAdvisor is a free service that will match you with a pro in your area.
4. Max out retirement contributions early
Instead of scrambling in March next year, contribute steadily all year.
This not only reduces your taxable income but gives your investments more time to grow.
Plus, you avoid the last-minute stress.
Pro Tip: Don’t wait on retirement saving. Every year costs you. Start today with matched contributions and watch your money grow! Sign up for a SoFi IRA and take advantage of compounding interest so you can retire comfortably. The longer you wait, the less you’ll earn. Get started today.
5. Track deductible expenses all year
Trying to reconstruct a year’s worth of deductions right before Tax Day is a nightmare. Whether it’s charitable giving, medical bills, or business costs, log them monthly.
This habit can make a big difference next spring.
Pro Tip: At the same time, slash expenses on dining, travel, eyeglasses, prescriptions and more with AARP — Just $15/year with auto-renewal. Join now and save hundreds.
6. Open a Health Savings Account (HSA)
If you have a high-deductible health plan, an HSA lets you save pre-tax money for medical expenses. It’s triple tax-advantaged and rolls over year to year.
Don’t wait until year-end to start saving.
Pro Tip: For example, if you have a high-deductible health plan, you should probably have a Health Savings Account. Check out Lively HSAs.
7. Organize your tax documents
Create a digital or physical folder labeled for next year’s taxes. Drop in W-2s, 1099s, receipts, and donation records as they arrive.
Stay on top of paperwork so nothing gets lost in the shuffle.
Pro Tip: While getting your finances in order, get your health in order, too. Life Line Screening reveals hidden risks so you can act early. Book a screening today and have peace of mind.
8. Eliminate high-interest debt
Credit card interest can quietly eat away at any refund you get — or make it harder to save for future tax payments. If your debt is climbing, act now.
Free help is available if you are worried about how much you owe.
Pro Tip: If you have more than $20,000 in unsecured debt, it can feel overwhelming. Get some professional help. National Debt Relief is a trusted source for free advice and assistance.
9. Revisit your insurance costs

If you’re self-employed, part of your home, auto, or health insurance might be deductible. Even if not, overpaying for coverage still hurts your bottom line.
Do a quick check to make sure your policy fits your budget.
Pro Tip: Make sure you aren’t paying more than you need for home insurance? Compare quotes from top providers today and make sure you’re not getting ripped off.
10. Make your money work year-round
Taxes shouldn’t be a once-a-year scramble. Build systems that support good habits and automate your savings throughout the year.
Aim to have amassed sufficient funds for whatever taxes you need to pay next Tax Day.
Pro Tip: Start by earning as much as possible on your emergency savings. For example, SoFi Checking is offering 3.8% interest, plus a potential $300 signup bonus. (May change without notice.)

Add a Comment