


Editor's Note: This story originally appeared on Boldin.
The marshmallow test is a psychological experiment that is supposed to determine a person’s ability to delay gratification and plan for a more abundant future. While managing your money isn’t all about sacrifice, it does involve balancing today’s priorities with tomorrow’s possibilities.
Let’s find out why financial planning is the ultimate marshmallow test and explore a few tips for how you can ace it.
What is the marshmallow test?
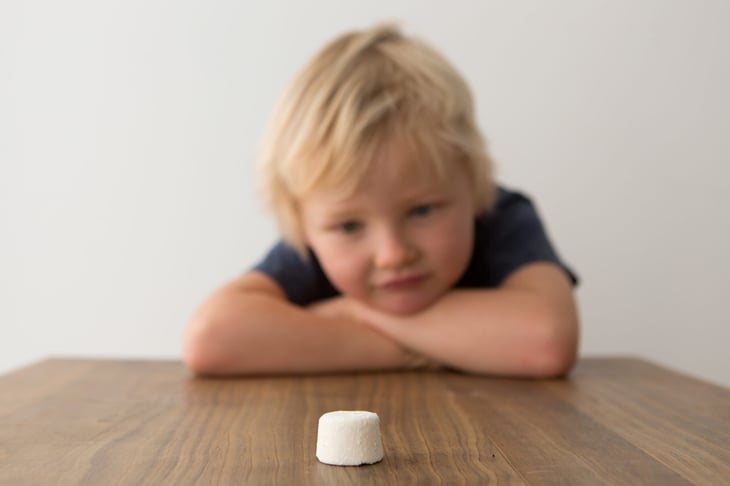
The marshmallow test is a now-famous psychological experiment designed to assess a child’s ability to delay gratification. The test was first conducted by psychologist Walter Mischel in the 1960s at Stanford University. The experiment involves placing a child in a room with a marshmallow (or another tempting treat) and giving them a choice:
- The child can eat the marshmallow immediately.
- If they can wait for a specified period (usually around 15 minutes), they will be rewarded with two marshmallows.
The primary goal of the experiment is to observe how long the child can resist the temptation of the immediate reward and, consequently, their ability to delay gratification.
Initial results from the marshmallow test and follow-up studies showed that children who were able to delay gratification had better life skills, academic performance, and social and emotional well-being later in life.
However, it is important to note that subsequent analyses have somewhat debunked the conclusions of the marshmallow test. Social trust, socioeconomic background, and other factors impacted the subject’s ability to succeed at the test.
Why managing your finances is the ultimate marshmallow test
While the actual marshmallow test may not be an accurate indicator, there is no doubt that planning for future abundance is a recipe for success in life.
Managing your money can be considered the ultimate marshmallow test because it requires many of the same skills and characteristics associated with success in the classic psychological experiment.
Delayed gratification
Both managing money effectively and the marshmallow test involve the concept of delayed gratification.
In personal finance, delaying immediate spending impulses in favor of saving and investing for future goals is crucial. This aligns with the idea of waiting for a larger reward in the marshmallow test.
Self-control
Successful money management requires self-control. This includes resisting the urge to make impulsive purchases, sticking to a budget, and avoiding behaviors that might jeopardize long-term financial goals. Self-control is a key factor in both scenarios.
Long-term planning

Like the marshmallow test, managing money effectively involves long-term planning. This includes setting financial goals, creating a budget, saving for retirement, and making strategic investment decisions.
Individuals who excel in these areas often demonstrate an ability to plan for the future, much like the children who could wait for the second marshmallow.
Coping with financial challenges and risks
Both the marshmallow test and personal finance involve dealing with challenges.
In personal finance, there are inherent risks that individuals may encounter, like unexpected expenses or market fluctuations. Being able to cope with these challenges, make informed decisions, and stay on course with long-term financial plans is essential.
Financial discipline
Success in managing money requires financial discipline. This encompasses consistently following a budget, saving regularly, and making informed choices about spending and investing. Financial discipline is a key trait shared by individuals who can delay gratification in the marshmallow test.
Goal setting
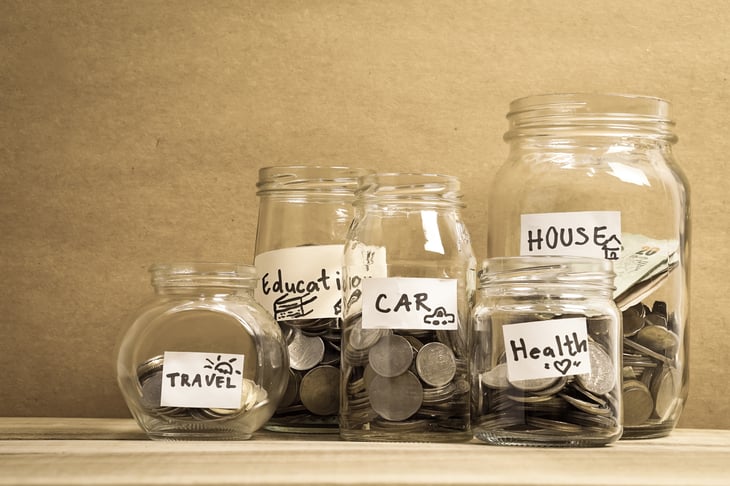
Both scenarios involve setting and working towards goals.
In the marshmallow test, the goal is to wait for the second marshmallow. In managing money, goals may include saving for a home, funding education, or achieving financial independence. The ability to set and work towards goals is a common factor.
The average Social Security start age and a real-world example of failing the financial marshmallow test
According to a report by the Center for Retirement Research at Boston College, 90% of Americans begin Social Security retirement benefits at or before their full retirement age. In fact, the most popular age to start is 62, the earliest age possible.
In many cases, this is an example of failing the personal finance marshmallow test.
If you have not yet started your Social Security, one of the best things you can do to live more comfortably is to wait until at least your full retirement age to claim your benefits.
- If you have reached full retirement age, which is 66 for people who were born between 1943 and 1959, you can access 100% of your benefits.
- For each year after that, up to age 70, your benefits increase by 8%, meaning you can access 32% more at age 70 than at age 66.
- If those benefits are tapped at a younger-than-full retirement age, they are reduced based on the number of months you receive benefits before you reach your full retirement age.
Example: If your full retirement age is 66, the reduction of your benefits at age 62 is 25%; at age 63, it is about 20%; at age 64, it is about 13.3%; and at age 65, it is about 6.7%, according to data from the Social Security Administration.
People who claim early are giving up nearly $100,000 in benefits over their lifetimes.
Tips for acing the financial marshmallow test and increasing your wealth
Next, let’s look at some tips to help you use the psychological hack of delayed gratification to build your wealth.

1. Quantify the benefits of delayed gratification
Olivia Mitchell is an economist at the Wharton School of the University of Pennsylvania. She tested ideas that may help people make the “right” – more profitable – decision about when to start Social Security.
Mitchell ran an experiment. She offered different kinds of incentives to people for delaying the start of Social Security benefits, and the results are very interesting:
- If potential Social Security recipients were told the difference in benefits they could receive if they claimed at age 62 vs delaying until age 66, 50% of people opted to delay.
- If people needed to work during the waiting time to start benefits, then only 46% opted to delay.
- However, if the researchers promised recipients that if they delayed their claim, then they would get $1,000 a month and a lump sum of $60,000 when they claimed at 66? Then the willingness to delay rose to 70.3% (no work while waiting) or 55.5% (working half-time while waiting).
So, it appears that getting a lump sum payout might be an interesting incentive to get people to delay starting Social Security.
2. Focus on the future reward, have a goal
For kids who succeed at the marshmallow test, they are focused on the goal of getting two marshmallows instead of one.
If you are trying to make good financial decisions to benefit your future wealth and security, you might want to focus on your retirement date or other financial goals. Do you want to buy a vacation home? Fund college for your children? Travel around the world.
Keeping your goals and priorities in mind as your future reward can help you make better decisions today.
3. Distract yourself

Some of the children who were successful at the marshmallow test would find ways to distract themselves from the temptation of the immediate reward. They looked away from the marshmallow, sang a song, or engaged in some other activity to take their minds off the temptation.
If you are faced with a short-term financial temptation, but need money for long-term goals, it is important that you learn to focus your brain on something besides your short-term desires. So, if you really want to splurge on a weekend ski trip but know it isn’t in your budget, refocus your short-term thinking on an activity that is more affordable and closer to home.
4. Use your imagination
Some of the children who were able to wait and get two marshmallows used their imaginations. They thought through the negative and positive future possibilities and examined the rewards and consequences of their actions:
- The disappointment of a researcher or a parent if they gave in to temptation.
- Their ability to savor two whole marshmallows.
You can imagine yourself in old age with less income in the future. And, you can visualize the joy of reaching a savings goal, enjoying a comfortable retirement, or achieving financial freedom. Imagining the future is a powerful and proven way to facilitate good long-term decision-making.
5. Build habits

It turned out that many of the children who held out for two marshmallows had already developed habits related to delayed gratification in their everyday life, making it easier to wait out for the extra marshmallow.
6. Manage emotions
Emotions, especially fear and greed, can wreak havoc on our financial status. It is important to understand the role emotions play in our financial decisions.
Financial decisions, whether related to investments, budgeting, or major purchases, should ideally be based on rational analysis and a clear understanding of one’s financial goals. Emotions such as fear, greed, or panic can drive individuals to make hasty decisions that deviate from their long-term plans.
For instance, during market volatility, the fear of potential losses might lead someone to sell investments hastily, missing out on potential long-term gains. On the other hand, excessive optimism and overconfidence can result in risky investments that may not align with one’s risk tolerance or financial objectives.
7. Seek accountability
Having someone to hold them accountable helped some children resist temptation.
Sharing your financial goals with a friend, family member, or financial advisor can also help you succeed with your money. It can be useful to seek support and encouragement to help you stay on track.
8. Create a plan

Children who had a plan, whether it was distracting themselves or imagining the marshmallow as something else, were more successful in delaying gratification.
Developing a financial plan that includes a budget, savings strategy, and investment plan is the ultimate way to ace the financial marshmallow test. And, the Boldin Retirement Planner is your roadmap. It can guide your financial decisions and keep you on track.

Add a Comment