


Many of the worst financial habits are also the most satisfying. Whether it is a brand-new gadget, an overpriced dinner, or a car that shines but guzzles gas, people often take pride in purchases that do more harm than good.
The trouble is that these habits may be disguised as necessities. They feel so ordinary that we justify the cost. And that makes them even more dangerous to our finances.
Pro Tip: Embrace delayed gratification and earn as much as possible on your emergency savings. For example, SoFi Checking is offering 3.8% interest, plus a potential $300 signup bonus. (May change without notice.)
1. Overpaying for phone service
Sticking with a big-name carrier might feel like a status move, but if your signal is weak and your bill is high, what are you really paying for? Bragging rights should not come with a monthly surcharge.
Trimming your phone bill is one of the quickest ways to free up cash without losing anything you need.
Pro Tip: If you pay more than $15 a month for your cell service, you can stop that right now. Click here to save a bundle.
2. Driving a luxury car that eats your savings
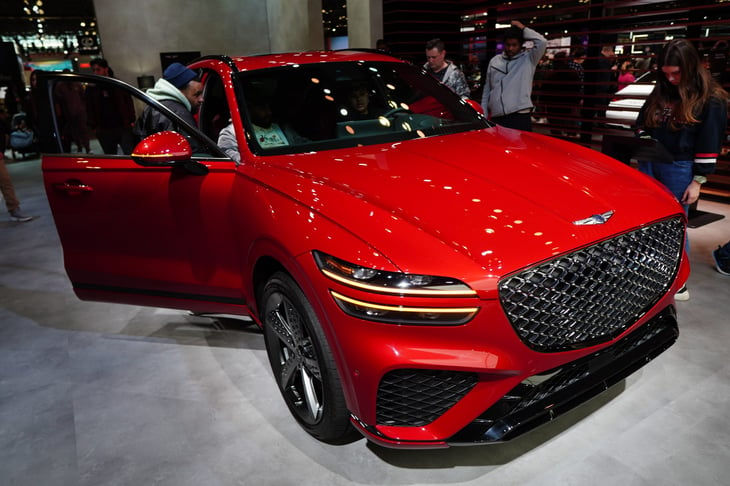
A fancy car might turn heads, but it can also empty your wallet faster than a speeding fine. High-end vehicles often bring high-cost repairs, expensive insurance premiums, and pricey maintenance.
A reliable ride that costs less to run could leave you with more cash in the tank.
Pro Tip: Regardless of your vehicle choice, car repair bills are not what they used to be. One auto shop told Consumer Reports their average job rose from $1,600 a decade ago to $4,000 today. Endurance gives you access to thousands of ASE-certified repair shops and pays the bill upfront, so you are only responsible for the deductible. Get a free quote today.
3. Going out to eat constantly
Dining out feels like a treat, but when it becomes your default, it devours your budget. Even casual meals can add up to hundreds per month.
Cooking more at home is not just healthier. It is one of the easiest ways to take control of your finances.
Pro Tip: That said, you can slash expenses on dining, travel, eyeglasses, prescriptions and more with AARP. Just $15 per year with auto-renewal. Join now and save hundreds.
4. Relying on your home for future cash
For many, home equity feels like a built-in backup plan. But that money is not magic. Accessing it responsibly depends on timing, market conditions, and your ability to qualify.
If you are banking on your home to bail you out later, make sure you know how and when that equity can actually help.
Pro Tip: Don’t tap into equity on a whim to free up more cash now. Store away the knowledge that if you are struggling with payments in retirement, a reverse mortgage can turn your home equity into tax-free cash for seniors 62 and older, no house sale required. Use the funds for medical bills, home repairs, or even that dream vacation without monthly payments.
5. Buying more insurance than you need
Being well-insured feels responsible, but overdoing it can quietly drain your finances. Coverage gaps matter, but so do overlaps that offer no real benefit.
Reviewing your policies regularly helps you balance protection with affordability. The goal is smart coverage, not the most expensive coverage.
Pro Tip: Did you know you can save up to $600 on your car insurance with this car insurance comparison site?
6. Ignoring old debts
Shoving unopened bills in a drawer might mean out of sight, out of mind, but interest keeps growing whether you look at it or not. Ignoring debt only makes the hole deeper.
Facing the numbers is the first step toward getting back in control.
Pro Tip: Open that drawer and face reality. If you have more than $20,000 in unsecured debt, get some professional help. National Debt Relief is a trusted source for free advice and assistance.
7. Buying on impulse and calling it self-care
Treating yourself occasionally is good for your mental health. But when impulse buys become a routine, you may be trading short-term comfort for long-term stress.
Real self-care includes protecting your peace of mind, and your wallet.
Pro Tip: Start by building a financial safety net that supports both. If you have a high-deductible health plan, you should have a Health Savings Account. Check out Lively HSAs.
8. Making snap decisions on investing
Handling your own money feels empowering until something gets missed. Without expert advice, you might be missing better options or exposing yourself to risk.
A financial advisor can help you see what you do not know to look for.
Pro Tip: Get some help if you have over $150,000 in savings, and consider talking to a professional financial advisor. Zoe Financial is a free service that will match you with a pro in your area.
9. Ignoring retirement planning
Telling yourself you will start saving “soon” is one of the most expensive habits out there. The longer you wait, the harder it gets to catch up.
The best time to start was yesterday. The second best time is right now.
Pro Tip: Start saving for retirement now and be glad later. Every year you wait costs you. Sign up for a SoFi IRA and take advantage of compounding interest so you can retire comfortably. The longer you wait, the less you will earn. Get started today.
When the feel-good fades, the cost stays
We all spend money on things that bring us joy. But if you’re smiling at checkout and wincing later when the bill arrives, it might be time to reassess.
Noticing these habits is the first step toward more mindful spending — and a calmer, more confident financial future.
And when it comes to essential expenses like health care, choosing wisely can make a big difference.
Pro Tip: Need Medicare help? Maximize benefits & save money. Get unbiased guidance. Compare plans today.

Add a Comment