


Ever wonder why you keep overspending, under-saving, or procrastinating on financial decisions? It’s not just a lack of discipline — it’s your brain working against you.
From dopamine traps to loss aversion, your psychology plays a major role in shaping money behavior. The good news? You can hack your brain’s default settings.
The science behind smart financial habits isn’t new — and that’s a good thing. Many of the techniques here are grounded in classic, still-relevant research that behavioral experts continue to rely on.
Use these psychology-backed tricks to flip your mental script and make smarter, more confident money moves.
1. Automate to defeat decision fatigue
Your brain resists decisions — even beneficial ones — because every choice you make depletes mental energy, a phenomenon known as decision fatigue, as reported by Baumeister & Tierney (2011).
That’s why automating key financial tasks like savings, debt payments, and investments is so effective.
By removing the need for repeated choices, you reduce cognitive strain and stop relying solely on willpower — which naturally weakens throughout the day, as demonstrated by Vohs et al. (2008) in their study on self-control and decision-making fatigue.
2. Rename your savings accounts
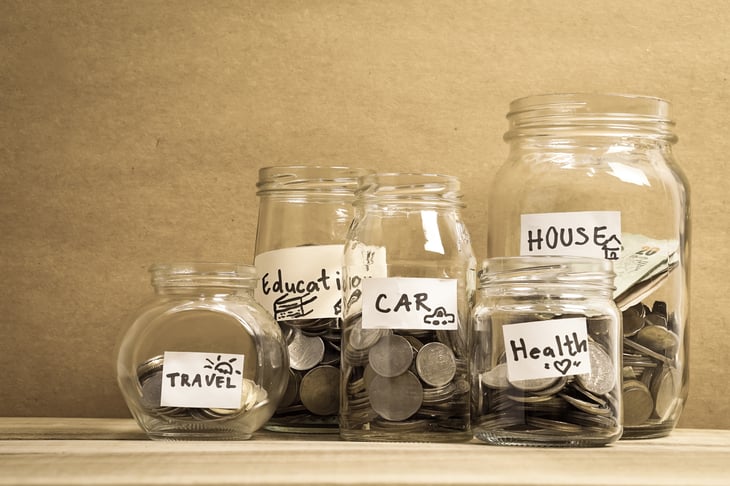
Labeling accounts with emotional or specific goals—like “Italy trip,” “Emergency Peace Fund,” or “Future Freedom” — creates a strong mental and emotional connection that makes saving more satisfying and purposeful.
According to research by Cheema and Bagchi (2011), this technique, known as “goal labeling,” increases the likelihood of follow-through by making the goal feel more personally meaningful.
It transforms saving from a mundane chore into an act of self-expression that aligns with your identity and future aspirations.
3. Use the 24-hour rule for spending
Impulse buys trigger a dopamine release, giving you a quick rush of satisfaction — but that feeling fades fast, often leaving behind regret.
According to research reported by McClure et al. (2004), this dopamine-driven response is linked to the brain’s reward system, which can override rational decision-making in the moment.
By waiting 24 hours before purchasing non-essentials, you interrupt the emotional cycle and give your logical brain time to assess the item’s true value.
4. Pay yourself first — and visualize it
Seeing money go directly into savings or investments right after payday helps rewire your brain to prioritize future gains over present temptations.
According to research by Thaler and Benartzi (2004), automating contributions — especially through programs like Save More Tomorrow — encourages long-term saving by removing the need for active decision-making.
This “out of sight, out of spend” approach reinforces the mindset that saving is a non-negotiable part of your financial routine, not an optional afterthought.
5. Make it hard to spend
Add intentional friction to your spending habits to disrupt impulsive behavior. Simple actions like deleting saved credit cards from shopping websites, unsubscribing from retail emails, or moving discretionary funds into a less accessible account can make a big difference.
Research by Shah, Mullainathan, and Shafir (2012) suggests that even small barriers in the decision-making process can reduce impulsive actions by forcing your brain to slow down and evaluate the consequences.
These built-in pauses give you time to reconsider each purchase more mindfully.
6. Break goals into micro-wins
Your brain craves accomplishment and thrives on progress. While big financial goals can feel overwhelming, breaking them into smaller, bite-sized targets — like saving $25 every Friday — can make them far more manageable.
Research highlighted by Amabile and Kramer (2011) shows that small, consistent wins boost motivation and enhance long-term commitment. Each small success builds momentum and makes your overall goal realistic and rewarding.
7. Set ‘anti-goals’ to avoid sabotage
Don’t just define what you want — also define what you’re trying to avoid. Framing goals as behaviors to steer clear of, such as “Don’t touch my emergency fund this month,” taps into your brain’s natural loss aversion.
As Kahneman and Tversky (1979) demonstrated, people are more motivated to avoid losses than to pursue equivalent gains. This mental shift helps you work harder to protect what you’ve already achieved rather than risk slipping backward.
8. Create visual progress charts
Visualizing your financial journey makes progress feel tangible and rewarding, whether it’s a coloring sheet, a jar of marbles, or a digital dashboard.
These visual cues remind you how far you’ve come, helping you stay focused, especially when motivation wanes.
Research by Locke and Latham (2002) emphasizes that visual feedback enhances goal performance by making achievements more visible and psychologically satisfying.
9. Name your future self
Studies have found that people are more likely to save when they perceive their future selves as real, relatable individuals.
By giving your future self a name, imagining their daily life, or even creating a vision board, you form a personal connection that boosts long-term thinking.
Hershfield et al. (2011) research reveals that this sense of continuity between present and future self significantly increases motivation to make better financial decisions today.
10. Stack new habits with old routines
Want to check your budget more consistently? Try linking the task to an existing habit, like reviewing your spending while sipping your morning coffee or right after brushing your teeth.
This approach, known as habit stacking, builds on established routines to make new behaviors easier to remember and sustain.
As Clear (2018) explains, habit stacking leverages contextual cues from daily life, increasing the likelihood that new habits will stick over time.
11. Reframe debt as lost freedom
Monthly payments can easily feel like a normal part of life — until you reframe them as barriers to your choices, flexibility, and financial independence.
By seeing debt not just as a number but as something that limits your freedom, paying it off becomes a motivating and empowering goal.
Research discussed by Sussman and Shafir (2012) shows that how we mentally frame debt significantly influences our urgency and behavior toward eliminating it.
12. Anchor your budget with one priority
Budgets often fail because they appear to be lists of restrictions and sacrifices. Instead, reframe your approach by identifying one meaningful priority, such as travel, early retirement, or buying a home, and designing your budget to support that goal.
This shift adds emotional resonance and personal motivation to your spending plan. Research by Ersner-Hershfield et al. (2009) highlights that when budgeting is anchored to long-term values, individuals are more likely to stay committed and make intentional financial choices.
13. Set a “money minute” reminder
You don’t need hours each day to manage your finances; just 60 intentional seconds can make a big difference.
Taking a moment to check your balance, review recent purchases, or reflect on your progress keeps financial awareness high and reduces the likelihood of costly surprises.
Karlsson, Loewenstein, and Seppi (2009) noted that frequent monitoring of financial accounts leads to better decision-making and greater control over spending behavior.
14. Reward small wins—strategically
Celebrating progress is essential for staying motivated, but it’s important that the reward doesn’t undo the progress you’ve made.
Planning small, intentional rewards, like a fancy coffee after a week of sticking to your meal plan, can reinforce good habits without derailing them.
As highlighted by Deci and Ryan (2000), well-timed, intrinsic rewards support ongoing motivation and help build lasting behavior change when they’re aligned with personal goals.
15. Use gamification to stay engaged

Your brain is wired to enjoy games, so turning financial goals into playful challenges can boost motivation. Incorporating levels, badges, or mini-milestones adds a sense of achievement and progress that keeps the process fun and engaging.
Even simple actions like checking off a savings calendar or competing with a friend can add a motivating layer of accountability. Research by Reeves and Read (2009) illustrates how game mechanics tap into reward systems in the brain, encouraging sustained engagement and behavior change.
16. Practice financial self-talk
What you say to yourself shapes how you behave. Replacing negative inner dialogue like “I’m terrible with money” with affirming statements such as “I’m learning to manage my money better” can rewire your brain over time.
As research by Beck (2011) shows, positive self-talk strengthens self-identity and builds confidence, two crucial ingredients for lasting financial growth and decision-making.
17. Set financial deadlines
Without a clear deadline, most goals tend to drift without direction. Giving your financial tasks a specific due date, such as “Cancel that unused subscription by Friday” or “Increase my 401(k) contributions by the 1st” — creates a sense of urgency that drives action.
Gollwitzer (1999) emphasized that setting time-bound intentions helps the brain form stronger implementation plans, making you more likely to follow through.
18. Build your money identity

It’s not just about what you do — it’s about who you believe you are. Shifting your mindset from focusing solely on outcomes to embracing an identity, like “I’m someone who manages money wisely” or “I’m the kind of person who pays bills on time,” lays a stronger foundation for lasting change.
Research by Oyserman, Fryberg, and Yoder (2007) points out that when behaviors align with a person’s self-identity, they’re more likely to be maintained over time.
Outsmart your instincts, not just your budget
Mastering money isn’t just about spreadsheets or strict rules — it’s about understanding how your brain reacts to fear, temptation, and reward. Real change becomes easier when you work with your psychology instead of against it.
The trick? Outsmart your instincts before they sabotage your success — and build habits that make your best financial self feel automatic.

Add a Comment