


A majority of states do not tax the property or other wealth you leave behind when you die. However, in some states, your estate or your heirs might owe estate or inheritance taxes if the value of your estate or their inheritance from you exceeds a certain amount.
Currently, a dozen states as well as Washington, D.C., have an estate tax, Nolo reports. Five states have an inheritance tax. One state has both an estate and inheritance tax.
What follows is a review of the states that levy an estate or inheritance tax and the amounts that determine whether an estate or inheritance is actually taxable in those states.
Estate taxes versus inheritance taxes
Estate taxes are taxes on a deceased person’s estate — that is, the value of the assets they owned at the time of their death.
Estate taxes exist at both the federal and state levels. The IRS taxes an estate if its gross value exceeds a certain amount, which is $15 million for the 2026 tax year. State threshold amounts are often much lower than the federal threshold, though.
Inheritance taxes are taxes on wealth that someone inherits, paid by the person who inherits it. There is no inheritance tax at the federal level, only in some states.
Connecticut
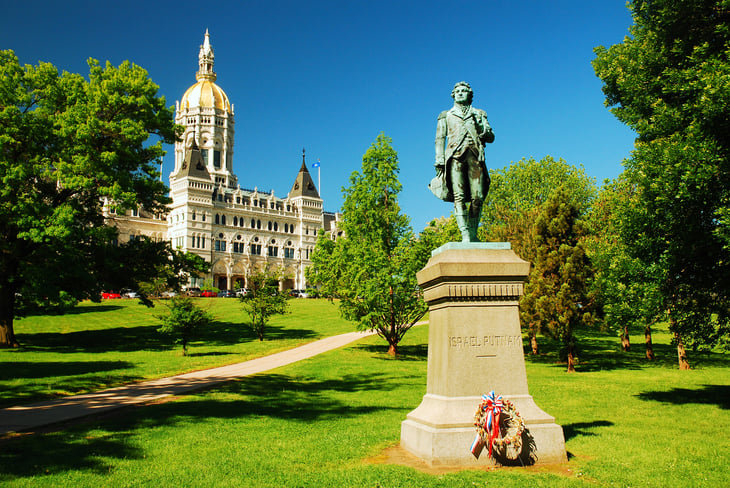
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Connecticut residents and even nonresidents — meaning people who didn’t live in the state but owned real estate or tangible personal property there when they died — may be subject to an estate tax if their taxable estate is worth more than $13.99 million (as of 2025).
Tax rate: 12%
To learn more: Visit Connecticut’s Department of Revenue Services website.
New York
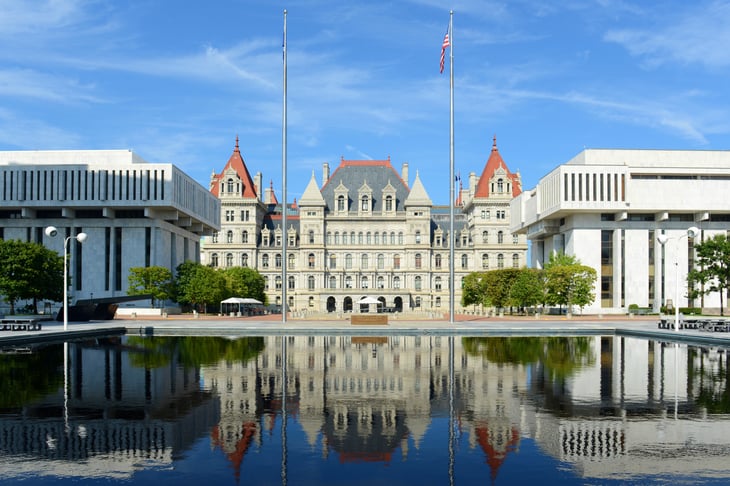
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Residents and nonresidents with estates valued at more than $7.35 million (as of 2026) may be subject to an estate tax.
Tax rate: Up to 16%
To learn more: Visit New York’s Department of Taxation and Finance.
Maine
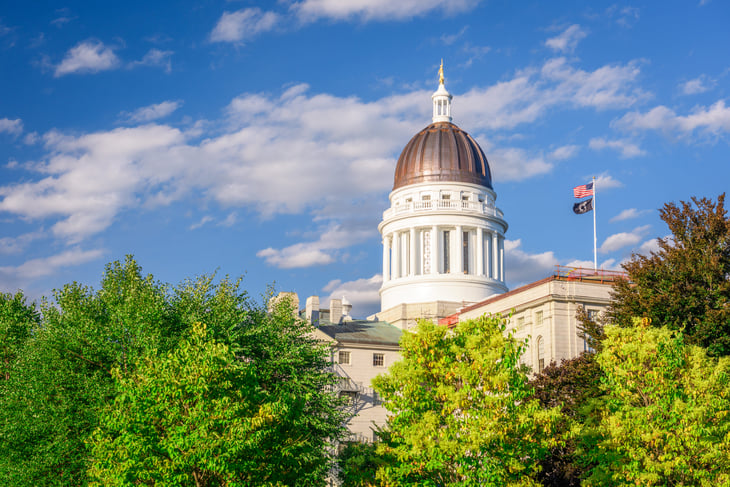
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Estates valued at more than $7.16 million (as of 2026) may be subject to an estate tax.
Tax rate: Up to 12%, depending on the taxable estate value
To learn more: See the state’s guidance document.
Hawaii
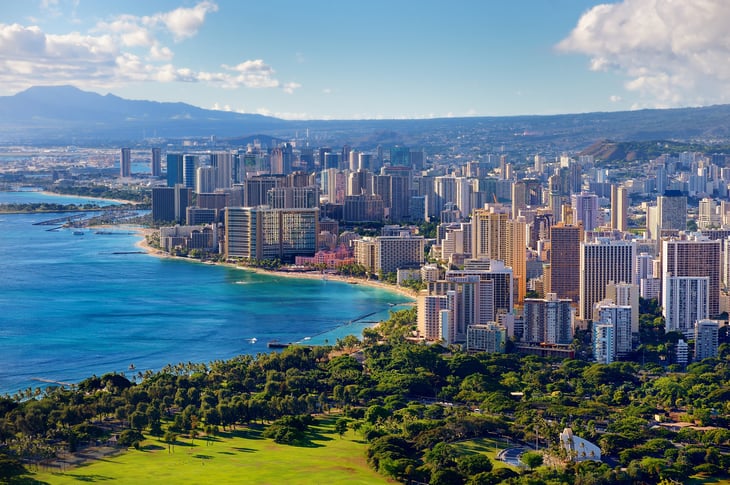
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Residents and nonresidents of Hawaii who leave a taxable estate of more than $5.49 million may owe an estate tax.
Tax rate: Ranges from 10% to 20%, depending on the value of the estate
To learn more: See Hawaii’s estate and transfer tax documents.
Vermont
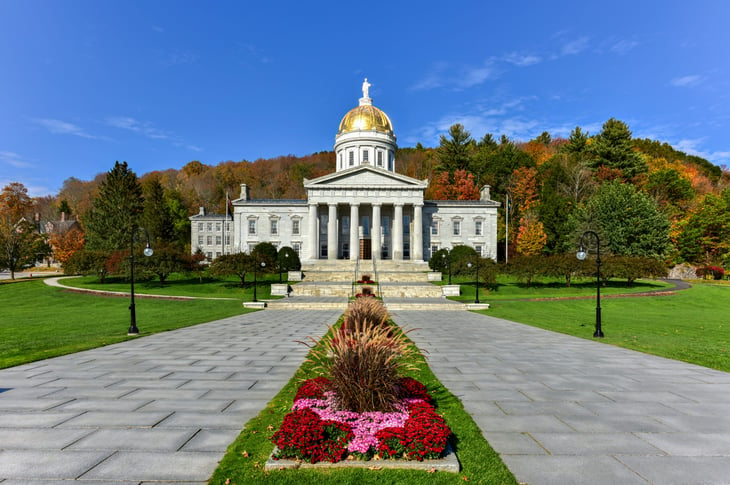
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Estates valued at more than $5 million could be subject to an estate tax.
Tax rate: 16%
To learn more: See the Vermont Department of Taxes’ Estate Tax page.
District of Columbia
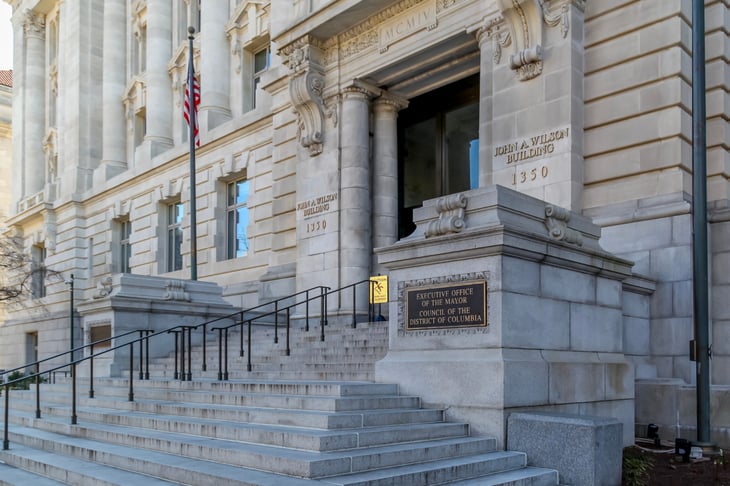
Type of tax that may apply to assets of D.C. residents upon death: Estate tax
Tax threshold: D.C. residents who leave an estate with a gross value of $4,873,200 or more (as of 2025) face an estate tax.
Tax rate: Ranges from 11.2% to 16%, depending on the value of the estate
To learn more: See D.C.’s estate tax forms and instructions.
Illinois
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Both residents and nonresidents of Illinois with a taxable estate of more than $4 million may be subject to an estate tax.
Tax rate: Up to 16%, depending on the taxable estate value
To learn more: Check out the Illinois attorney general’s Estate Taxes page.
Minnesota
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Estates with a gross value of more than $3 million must file an estate tax return and may be subject to an estate tax.
Tax rate: Ranges from 13% to 16%
To learn more: Visit the Minnesota Department of Revenue’s Estate Tax page.
Washington
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Estates with a gross value of more than $3 million (as of July 1, 2026) could be subject to an estate tax.
Tax rate: Ranges from 10% to 20%
To learn more: Visit the Washington Department of Revenue’s Estate Tax page.

Rhode Island
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: Estates with a gross value of more than $1,838,056 (as of 2026) could be subject to an estate tax.
Tax rate: Up to 16%
To learn more: Visit the Rhode Island Division of Taxation’s Estate Tax page.
Oregon
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: If a resident or nonresident’s estate value is more than $1 million, an estate tax might be due.
Tax rate: Ranges from 10% to 16%
To learn more: Visit the Oregon Department of Revenue’s estate tax page.
Massachusetts
Type of tax that may apply to assets of this state’s residents upon death: Estate tax
Tax threshold: For estates of residents and nonresidents valued at more than $2 million, an estate tax might be due before the amount can be distributed.
Tax rate: Up to 16%
To learn more: Review Massachusetts’ Estate Tax Guide.
Pennsylvania
Type of tax that may apply to assets of this state’s residents upon death: Inheritance tax
Tax threshold: In general, any inheritance could be subject to Pennsylvania’s inheritance tax unless excluded by law. Two notable exclusions are for assets transferred from a deceased spouse to a surviving spouse, or from a deceased parent to a child age 21 or younger.
Tax rate: Up to 15%, depending on the relationship between the heir and the deceased
To learn more: See the Pennsylvania Department of Revenue’s Inheritance Tax page.
Nebraska
Type of tax that may apply to assets of this state’s residents upon death: Inheritance tax
Tax threshold: Inheritances that exceed the amounts of $25,000, $40,000 or $100,000, depending on the heir’s relationship to the deceased, may be subject to Nebraska’s inheritance tax.
Tax rate: Up to 15%, again depending on the relationship
To learn more: Review the basics of Nebraska’s laws and tax rates.
Kentucky
Type of tax that may apply to assets of this state’s residents upon death: Inheritance tax
Tax threshold: “All property belonging to a resident of Kentucky is subject to the tax except for real estate located in another state,” according to the state. “Also, real estate and personal property located in Kentucky and owned by a nonresident is subject to being taxed.” There are some exemptions based on an heir’s relationship to the deceased, though.
Tax rate: Up to 16%, depending on the heir’s relationship to the deceased
To learn more: Visit the Kentucky Department of Revenue website.
New Jersey
Type of tax that may apply to assets of this state’s residents upon death: Inheritance tax
Tax threshold: Inherited property with a value of more than $500 may be subject to New Jersey’s inheritance tax, depending on the heir’s relationship to the deceased. However, there are exemptions based on the amount and that relationship.
Tax rate: Ranges from 11% to 16%, depending on the inherited property value and the heir’s relationship to the deceased
To learn more: Visit the New Jersey Division of Taxation’s confusingly titled “Inheritance and Estate Tax” page. (The state’s estate tax was repealed in 2018.)
Maryland
Type of tax that may apply to assets of this state’s residents upon death: Estate and inheritance taxes
Tax threshold: Gross estates valued at $5 million or more may be subject to a tax.
Inheritance taxes may be due based on the relationship of the heir to the deceased. Some related individuals, including spouses and children, generally are exempt from Maryland’s inheritance tax.
Tax rate: Up to 16% for the estate tax and 10% for the inheritance tax
To learn more: Visit the Comptroller of Maryland’s Estate and Inheritance Tax Information page.

Add a Comment