


For many, Lent is a time to give up something as a spiritual practice. No matter your faith—Buddhist, Hindu, Jewish, Muslim, or none at all—some financial habits are worth breaking for a stronger financial future.
These nine behaviors hurt your financial health all year, and there’s no better time to break free from them.
No religious calendar is needed, just a desire for a healthier financial future.
Pro Tip: Financial habits improve faster with professional guidance. If you’ve got at least $100,000 in investments, check out a free service called SmartAsset. You fill out a short questionnaire and instantly get matched with up to three vetted financial advisors in your area.
1. Not saving for retirement

Every year you don’t save for retirement means thousands in lost growth you’ll never get back. Some people work years longer than planned or living on much less because they started too late.
Early savings grow exponentially more than later ones. Someone who starts at 25 investing $5,000 yearly will likely end up with far more than someone starting at 45, even if the late starter puts away twice as much each year.
Make retirement saving non-negotiable and automatic, no matter your age.
Pro Tip: Start saving for your post-career years with matched contributions and watch your money grow! Sign up for a SoFi IRA and take advantage of compounding interest so you can retire comfortably. Get started today.
2. Going into debt for luxuries
When you finance non-essential purchases, today’s pleasures become tomorrow’s financial headaches.
Paying interest on vacations, electronics, or fashion items multiplies their actual cost while preventing you from building wealth.
This habit often results from social pressure and a desire for things now. Break this cycle by using cash for non-essentials and being honest about a need versus a want.
Pro Tip: Avoid high-interest debt traps for essential purchases when cash is tight. Get 0% intro APR for purchases and balance transfers for 15 months, plus earn a bonus of 20,000 miles once you spend $500 on purchases within 3 months from account opening.
3. Investing in only one type of asset
Putting all your money in one type of investment—whether stocks, real estate, or cryptocurrency—puts your financial future at unnecessary risk.
Even strong-performing investments can experience long downturns, sometimes right when you need your money most.
This habit often starts by chasing recent performance or sticking with what feels familiar. Break it by spreading your investments across different types of assets so that problems in one area don’t wreck your entire financial plan.
Pro Tip: Explore diversification options like precious metals investments, with opportunities to receive up to $10,000 in free metals through qualified purchases. If you’re over 50 and curious about investing in Gold, now is a great time to get your FREE 2025 Gold Information Kit and protect your future with physical precious metals!
4. Skipping preventative health screenings
Avoiding routine health checkups saves money today but can cost a fortune later.
Health problems caught early usually require less expensive treatment and have better outcomes, while advanced conditions often trigger massive medical bills that even good insurance won’t fully cover.
Late diagnosis also can hurt your income through extended time off work or even disability. View preventative care as an investment, not an expense, and prioritize regular screenings.
Pro Tip: Life Line Screening reveals hidden risks so you can act early. Book a screening today and have peace of mind.
5. Not checking your hearing
Untreated hearing issues can cause workplace misunderstandings, lower productivity, and even early retirement.
Research shows untreated hearing loss leads to higher healthcare costs and faster cognitive decline.
Many people avoid hearing tests because of cost or stigma, not realizing today’s hearing solutions are more effective and less noticeable than ever.
Pro Tip: Thanks to new FDA rules, people with hearing difficulties can now purchase top hearing aids without a prescription, making better hearing more accessible and affordable.
6. Using home equity loans for everyday expenses
Using your home equity to pay for routine expenses puts your house at risk while hiding budget problems. This approach temporarily masks the issue while steadily eating away at your most valuable asset.
This habit often starts as a “just this once” solution before becoming a recurring pattern.
Set clear rules about home equity—save it for true investments in your home, not lifestyle maintenance—and create a spending plan that matches your actual income.
Pro Tip: Home equity loans are ideal for house improvements. To explore responsible options, see how much you can get, how fast you can get it and how little you'll pay for legitimate wealth-building purposes.
7. Ignoring credit reports and scores
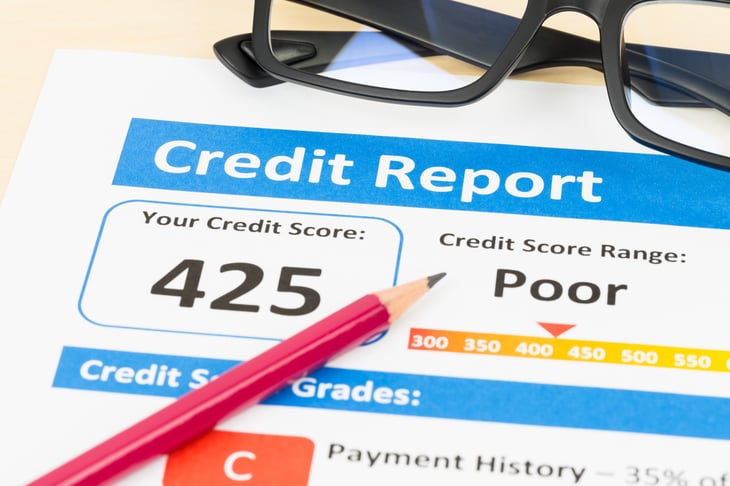
Not monitoring your credit regularly leaves you vulnerable to identity theft and higher interest rates.
Errors or fraud can damage your credit for months before you notice, while outdated negative items might stay on your report longer than legally allowed without your intervention.
Check your reports from all three bureaus yearly and review your scores quarterly to spot problems and improvement opportunities.
Pro Tip: Poor credit scores can drain your finances through higher interest rates. If debt has become overwhelming, professional guidance can help. National Debt Relief offers free advice and assistance for those with more than $20,000 in unsecured debt.
8. Paying avoidable banking and investment fees
Unnecessary financial fees slowly drain your wealth without giving you anything in return. From monthly account fees to high-expense investment funds, these seemingly small costs add up dramatically over time.
Even modest fee reductions can mean tens of thousands more in retirement savings.
Break this habit by reviewing all your financial accounts yearly to identify unnecessary costs, then consolidate or switch providers. Question every fee to determine if it’s worth the value or can be eliminated.
Pro Tip: SoFi Checking offers 3.8% interest on your money plus a potential $300 signup bonus for new accounts, with no hidden fees to drain your balance. (May change without notice.)
9. Neglecting insurance coverage reviews

Letting insurance policies auto-renew without regular review leads to paying too much or having dangerous coverage gaps.
As your life changes, your insurance needs change too—but your policies stay the same unless you update them.
Schedule annual reviews of all policies, get comparison quotes, and adjust coverage to match your current situation. Look for multi-policy discounts whenever possible.
Pro Tip: Many people overpay for car insurance by not shopping around regularly. You might save up to $600/yr by using a car insurance comparison site to find better rates for the same coverage in just minutes.
Breaking destructive habits creates lasting financial freedom
Giving up these nine financial habits doesn’t require religious observance, but it does take discipline and a focus on long-term benefits over short-term satisfaction.
Whether you’re giving these up for Lent or simply for your financial well-being, the time to break destructive money habits is now.
The improvements extend beyond any temporary period, potentially changing your relationship with money for decades.
Pro Tip: As you improve your financial habits, protect your legacy. Where there's a will, there's a way to ensure your hard-earned assets go exactly where you want them, saving your loved ones time, money and stress.

Add a Comment