


Home insurance is a must for homeowners, but many people don’t realize how much protection their policy actually includes.
Beyond the basics like fire or theft, most standard policies come with hidden benefits that can save you thousands.
If you haven’t reviewed your policy lately, you could be missing out. Here are 10 often-overlooked perks already built into your home insurance.
1. Spoiled food replacement
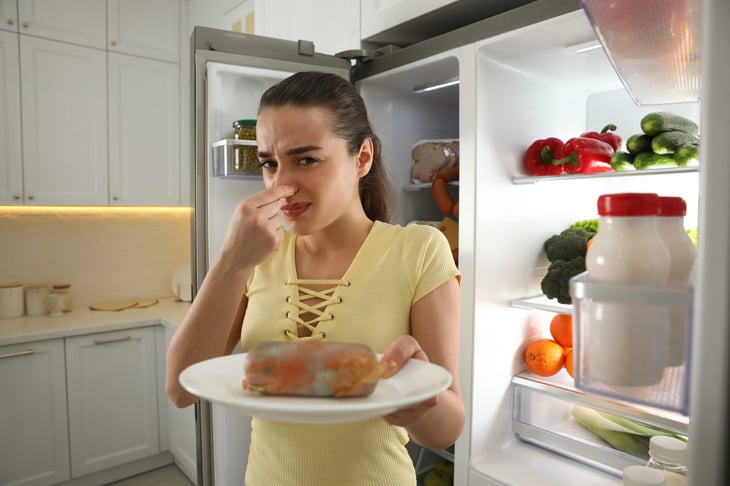
If a power outage spoils everything in your fridge or freezer, your homeowners or renters insurance policy may reimburse you for the lost groceries — sometimes covering up to $500 or more, depending on your coverage.
Just make sure to document the incident thoroughly and save your receipts if possible, as this can help support your claim and speed up the reimbursement process.
2. Temporary relocation coverage

If your home becomes uninhabitable due to a covered event, your insurance policy may help pay for hotel bills, restaurant meals, laundry, and other necessary living expenses while you’re temporarily displaced.
This benefit is known as “loss of use” or Additional Living Expenses (ALE). And just like with housing, unexpected costs can add up quickly when you’re forced out of your routine — even while you’re on the road or staying with friends or family.
3. Dog bite liability
If your dog bites someone — even off your property — your policy may help cover medical expenses and legal fees, depending on the breed and circumstances.
It’s one of the most overlooked protections in a standard homeowners policy. You can go even further for your furry friend by using a pet insurance credit card that helps cover vet bills while earning rewards on pet-related purchases.
4. Identity theft protection
Some home insurance policies include optional or built-in identity theft protection.
This added benefit can help cover legal fees, lost wages, and recovery-related expenses if you’re targeted by fraud — potentially saving you thousands during the recovery process.
It’s a smart idea to ask your insurance provider whether this coverage is already included or if it can be added for a small additional cost.
5. Items stolen from your car
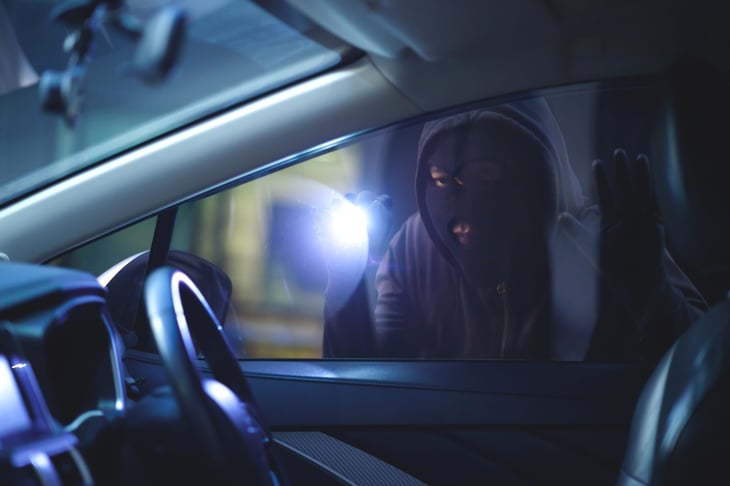
If your laptop, phone, or other personal valuables are stolen from your car, don’t assume your auto insurance will cover the loss — in most cases, it won’t. However, your homeowners or renters insurance policy might step in to help.
This kind of protection typically applies even if the theft happens far from home, such as in a parking lot, at work, or while traveling. Just be sure to file a police report and document the loss for your claim.
6. Fallen tree removal
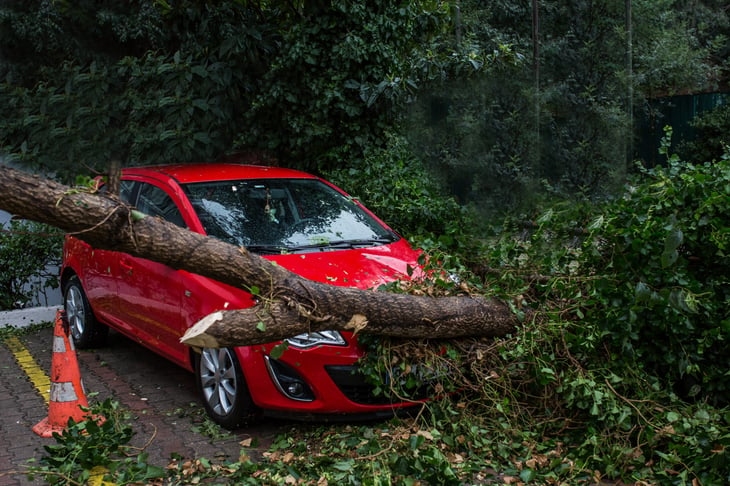
Most homeowners insurance policies will cover the cost to remove trees that fall due to wind, lightning, or another covered peril — even if the fallen tree didn’t actually damage your house or other structures.
Coverage limits and specific conditions can vary by policy, but it’s important to know that cleanup alone can easily cost thousands of dollars, especially if heavy equipment or emergency services are needed.
7. Accidents away from home
Your personal liability coverage often follows you wherever you go — which means if you accidentally injure someone at the park or damage an expensive item at a friend’s house, your homeowners or renters insurance may help cover the costs.
This kind of protection is especially valuable for families with active kids, where accidents can happen anytime, anywhere.
And if you’re thinking about safeguarding your family’s future beyond everyday mishaps, having a life insurance policy in place is a smart and essential step.
8. Coverage for college students
If your child is away at college, their personal belongings may still be covered under your homeowners or renters insurance policy — as long as they live in a dorm and are still considered a dependent.
This built-in coverage can save you the added expense of purchasing a separate renter’s policy for them.
And when it comes time to furnish their space or replace stolen or damaged items, using a credit card with cash-back or rewards benefits can help turn every purchase into extra savings.
9. Upgrades required by code
If you ever need to rebuild your home after serious damage, and local building codes require you to make updates — such as upgrading electrical systems, plumbing, or insulation — your insurance policy may help cover those additional expenses.
This type of protection is called “ordinance or law” coverage, and it can be a financial lifesaver when you’re dealing with unexpected code compliance costs during repairs or reconstruction.
10. Legal fees for lawsuits

If someone sues you for an injury or property damage and the incident falls under your liability coverage, your insurance may cover the cost of your legal defense — even if the claim turns out to be groundless or exaggerated.
This benefit alone can save you tens of thousands of dollars in legal fees and court costs. It’s another reason to regularly review your coverage and consult with a professional financial advisor to ensure you’re fully protected.
Check your policy to see what’s covered
Many homeowners pay for insurance month after month without realizing how many valuable extras are already built into their policy. Taking the time to review your current coverage — or exploring options with a new provider — can reveal opportunities for better protection and potential savings.
Don’t leave important benefits on the table simply because you weren’t aware they existed. From hidden coverages to overlooked discounts, a closer look can make a big difference.
Be sure to compare home insurance rates regularly to ensure you’re getting the best value for your money.

Add a Comment