


Over the past decade or more, everything from life expectancy to savings expectations has shifted dramatically.
What was once considered a secure retirement may no longer be enough. Retirement has changed, and for those planning their future, that may mean doing things differently.
1. The Average Retirement Age is Rising

Retiring at 65 was the norm, but today, more people are working into their late 60s and even 70s. Many delay retirement due to financial necessity, healthcare costs, or a desire to stay active in the workforce.
Life expectancy has increased since 1999, and fewer jobs offer traditional pensions, making it harder to retire comfortably without additional savings. Without the security of pensions, it’s essential to prioritize saving for retirement to ensure a financially stable future.
Pro Tip: Earn as much as possible on your emergency savings to grow your wealth even before retirement. For example, SoFi Checking is offering 4% interest, plus a potential $300 signup bonus—helping you earn more while building your financial cushion. (Rates may change without notice.)
2. Social Security Benefits Cover Less
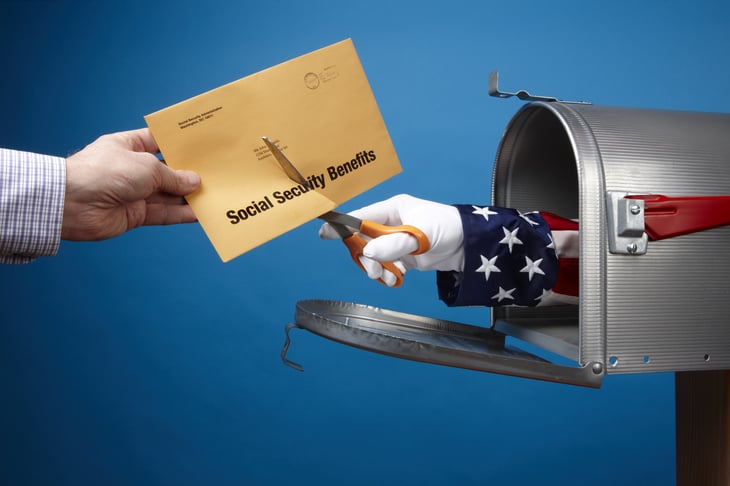
Social Security remains a critical part of retirement income, but its purchasing power has diminished. Benefits have not kept pace with inflation, forcing retirees to rely more on personal savings.
In 1999, Social Security was often enough to cover basic expenses. Today, rising healthcare costs and housing prices mean it plays a smaller role in overall financial security.
3. Retirement Savings Expectations Have Skyrocketed
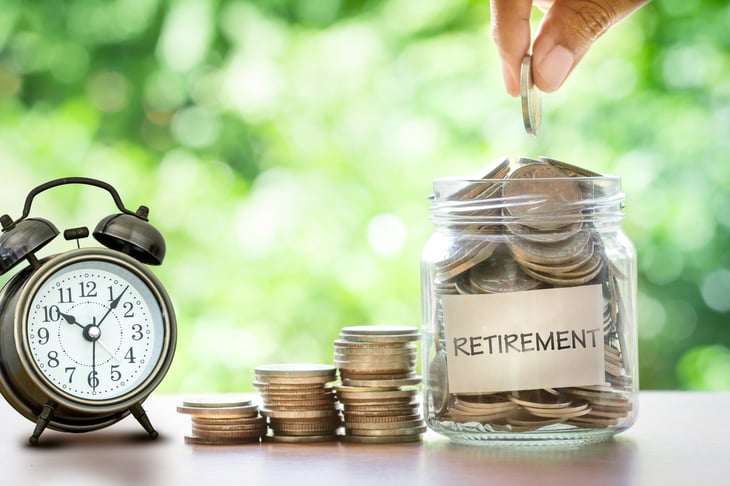
The recommended retirement savings target has soared.
In the late 1990s, many experts suggested saving $500,000 for a comfortable retirement. Financial planners often recommend $1.5 million or more due to increased costs and longer lifespans. With inflation, rising healthcare expenses, and the increasing cost of living, building a more substantial savings cushion is essential to maintain a comfortable retirement lifestyle.
Many retirees are turning to investment strategies to help build long-term financial stability. By diversifying investments, they are working to ensure their savings outpace inflation and last throughout retirement.
Pro Tip: One modern way to diversify is with real estate and venture capital. Companies like Fundrise offer investments as small as $10, making it easy to get started and build your portfolio for long-term growth.
4. Healthcare Costs Have Exploded
Medical expenses for retirees have climbed dramatically. The cost of Medicare premiums, long-term care, and prescription drugs is far higher today than before the turn of the century.
Many retirees underestimate their healthcare needs, leading to financial strain in later years. With healthcare costs increasing, it’s crucial to plan and save specifically for medical expenses during retirement. Starting early and using tools like Health Savings Accounts (HSAs) can provide valuable financial support when the time comes.
5. Working in Retirement is the Norm
In 1999, retirement meant leaving the workforce for good. In 2025, many retirees continue working part-time or starting side gigs to supplement their income. Whether due to financial need or personal fulfillment, today’s retirees are redefining what it means to retire.
Many find that staying active in the workforce helps with finances and provides a sense of purpose and connection. This shift leads to new retirement models, where flexibility and continued engagement are key elements.
Pro Tip: If you want to earn extra income, even in retirement, consider side gigs like online tasks. Earn up to $1000 per month doing simple tasks with KashKick—a great way to stay financially flexible while staying engaged.
The New Retirement Reality
Retirement now looks nothing like it did in 1999. From higher costs to changing work expectations, today’s retirees must navigate an entirely different landscape.
Planning, diversifying savings, and staying informed can help ensure financial security, no matter how the future changes.

Add a Comment