


A personal loan can be a powerful financial tool when used wisely. Many people associate loans with emergencies, but they have a wide range of strategic uses that could benefit your financial situation.
Whether you’re looking to consolidate high-interest debt, improve your credit score, or invest in your future, the right personal loan can help you achieve your goals without unnecessary financial strain.
Unlike credit cards, which often carry steep interest rates, personal loans usually come with fixed rates and structured repayment terms. This predictability makes them a valuable alternative for financing certain expenses while maintaining control over your budget.
Here are seven surprising ways a personal loan might be your best financial move.
1. Consolidating High-Interest Debt Saves You Money
If you carry multiple credit card balances with high interest rates, a personal loan can be a smart way to consolidate that debt. By rolling your existing debts into one loan with a lower fixed interest rate, you could reduce your total interest payments and simplify your finances.
You’ll have one predictable monthly payment instead of juggling multiple due dates and minimum payments.
Additionally, consolidating credit card debt with a personal loan could improve your credit score. Credit card debt impacts your credit utilization ratio—the percentage of available credit you use. By paying off credit cards with a personal loan, you lower this ratio, which may positively affect your credit score.
Pro Tip: Struggling with significant debt? If you have more than $20,000 in unsecured debt, it’s time to get expert help. Professional guidance can create a tailored plan to reduce debt and lower those stressful monthly payments. National Debt Relief is a trusted source for free advice and assistance—get back on track with a clear strategy.
2. Covering Medical Expenses Without Sky-High Rates
Medical bills can add up quickly, and hospitals or providers may charge high interest on unpaid balances.
Rather than relying on expensive medical financing plans or maxing out credit cards, a personal loan with a lower interest rate can provide a more affordable way to manage these expenses.
Medical costs aren’t always predictable, but a personal loan allows you to take control of the repayment schedule. You can spread payments out over a set period, ensuring your healthcare costs don’t overwhelm your monthly budget.
3. Making a Major Purchase Without Draining Savings
Significant expenses—such as replacing an essential appliance, buying new furniture, or funding a necessary home improvement—can be difficult to cover upfront. A personal loan lets you finance these purchases without depleting your savings or emergency fund.
Unlike using a credit card, which may carry a high variable interest rate, a personal loan provides structured repayment terms with a fixed interest rate. This can help you manage large expenses while maintaining financial stability.
Pro Tip: Looking for a smarter way to finance big purchases? Instead of racking up high-interest debt, consider a credit card with a 0% intro APR—giving you time to pay down your balance without extra fees while earning up to 10% cash back in your first year, turning necessary expenses into potential rewards. Get a rare card with 0% intro APR to ease debt pressure and start making your money work for you!
4. Boosting Your Credit Score With Timely Payments
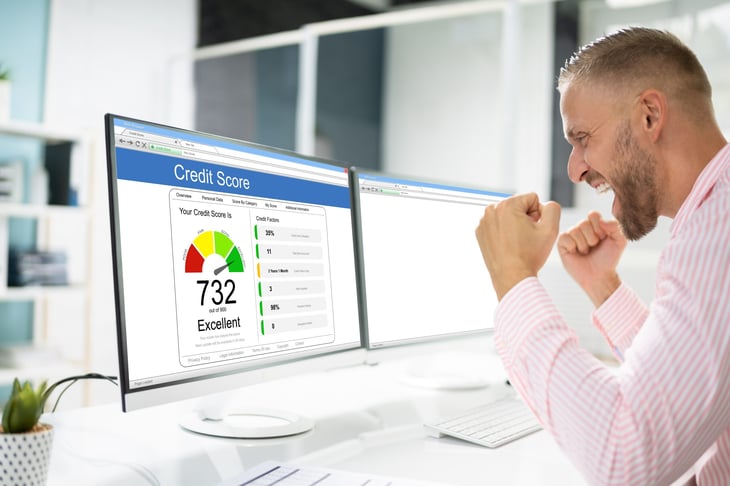
A personal loan can be a key tool for strengthening your credit profile. Various factors, including your credit mix and payment history, influence your credit score.
Adding an installment loan—such as a personal loan—can diversify your credit mix and show lenders that you can responsibly manage different types of debt.
Making consistent, on-time payments on a personal loan demonstrates financial responsibility and can improve your credit history over time. This could make it easier to qualify for better interest rates on future loans, including mortgages or auto financing.
Pro Tip: Want to build credit while avoiding sky-high interest? A 0% intro APR credit card lets you pay down balances without added interest, boosting your credit score while keeping your finances stress-free. This is one of the best cards of 2025, offering 0% interest until nearly 2027. Get a 0% intro APR credit card and pay no interest until nearly 2027—a smart move for debt management and financial flexibility.
5. Funding Career Advancement for Better Earnings
Investing in yourself can be one of the best financial decisions you make. If you need additional training, certification, or education to advance your career, a personal loan can provide the funds necessary to boost your earning potential.
Unlike student loans, which are typically limited to tuition costs, a personal loan can be used for a broader range of expenses, including professional development courses, industry certifications, and job-related equipment.
If your goal is to qualify for a higher-paying job or launch a business, this investment could provide a solid return in the long run.
6. Covering Relocation Costs Without Stress
Moving for a new job, downsizing, or relocating to a different city can be expensive. The expenses can quickly add up between security deposits, hiring movers, travel costs, and temporary housing.
A personal loan can help cover these upfront costs, allowing you to relocate smoothly without financial strain. Rather than draining your savings or putting the entire cost on a high-interest credit card, a loan provides structured repayment, helping you stay financially stable during your transition.
7. Seizing a Limited-Time Investment Opportunity
Sometimes, a great financial opportunity requires quick action. Whether it’s a real estate deal, a business investment, or an opportunity to purchase something at a discount, having access to funds at the right time can make a big difference.
A personal loan can provide the liquidity needed to seize an opportunity, especially if the potential returns outweigh the cost of borrowing. However, it’s essential to calculate the risks carefully—using a loan for investment purposes should always be based on sound financial reasoning.
Think Beyond Emergencies for Smart Borrowing
A personal loan isn’t just a last resort option for emergencies—it can be a strategic financial tool when used wisely. From lowering debt costs to funding career growth, the right loan can work in your favor if you plan carefully.
Before taking out a loan, compare interest rates, check repayment terms, and ensure that the monthly payments fit within your budget. Borrow only what you need and have a clear repayment plan.
When managed responsibly, a personal loan could be one of the smartest financial moves you can make.

Add a Comment