


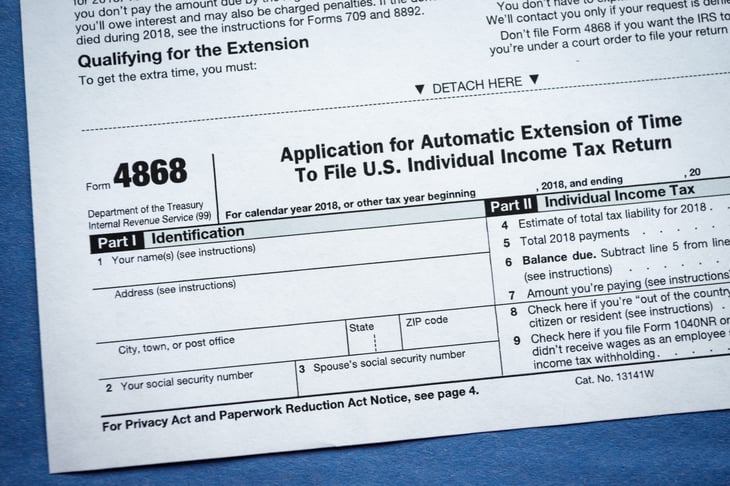
If you’re among the millions who requested an extension this year, follow these steps to minimize costs, maximize deductions, and avoid costly mistakes as the October filing deadline approaches.
Double-check your return for opportunities that could save you thousands of dollars and prevent errors.
Pro Tip: Looking to save money and enhance your investment earnings? Over 80% of new investors struggle without guidance? With EchoTrade, you can seamlessly copy the trades of top wealth managers.
Echo Trade is a subscription service providing access to investment strategies from professional money managers. Echo Trade is not an investment advisor, brokerage firm, or fiduciary. Investing carries risks, including loss of principal. Past performance doesn't guarantee future results. Users must connect a compatible brokerage account to use trading functionality.
1. Pay estimated taxes to reduce penalties
You may accrue penalties and interest if you haven’t paid your entire tax liability by the original April deadline. The IRS charges a failure-to-pay penalty of 0.5% per month on unpaid taxes, up to 25% of the unpaid amount, plus interest.
Making an estimated payment now can stop these penalties from growing larger. Even a partial payment may reduce the balance on which penalties are calculated.
The IRS offers online payment options that make this process quick and straightforward, allowing you to minimize the financial impact of your extension.
Pro Tip: Tax season can strain your finances. If you need funds to cover tax payments or other expenses, there are good options available. Explore financial solutions here to help you manage your tax obligations without breaking the bank.
2. Maximize retirement contributions
One significant advantage of filing with an extension is the extra time to make retirement contributions that can reduce your taxable income for the previous tax year.
You can still contribute to certain retirement accounts like SEP IRAs, solo 401(k)s, and SIMPLE IRAs for the previous tax year until your extended filing deadline.
This strategy can potentially reduce self-employed individuals’ taxable income by tens of thousands of dollars. Check with your financial advisor about contribution limits and eligibility based on your situation.
Pro Tip: Effective retirement planning requires expert guidance, especially when using tax strategies. Professional advice can optimize your tax situation if you’ve accumulated over $100,000 in savings. SmartAsset offers a free service that matches you to a vetted fiduciary advisor in less than 5 minutes.
3. Review last year’s return for missed opportunities
Take time to thoroughly compare your previous year’s tax return with your current draft. Many taxpayers overlook deductions or credits they’ve claimed before.
Look specifically for inconsistencies in itemized deductions, business expenses, or credits that appeared on previous returns but might be missing from your current preparation.
Tax laws change, but this review often reveals legitimate deductions you may have forgotten to include. This simple review can sometimes uncover hundreds or even thousands in tax savings.
Pro Tip: Consider protecting your financial future with diversified assets while reviewing your tax situation. Many financial experts recommend hedging against inflation and economic uncertainty by opening a gold IRA—a smart complement to your tax planning strategy.
4. Document often-overlooked deductions
The extra time an extension provides allows you to thoroughly document deductions that many taxpayers miss, such as charitable contributions, medical expenses exceeding 7.5% of your adjusted gross income, and state sales taxes.
Don’t forget about smaller deductions that add up, like professional subscription services, continuing education costs, and home office expenses if you’re self-employed.
Take time to check bank and credit card statements for these expenses. Even small deductions of a few hundred dollars can add up to significant tax savings.
Pro Tip: While organizing tax documents, don’t forget to review your monthly expenses for additional savings. Many people overpay for basic services like cell phones. Click here to save a bundle if you’re paying more than $15 a month for your cell service.
5. Consider amending previous returns
If you discover you’ve missed significant deductions or credits in previous years while preparing your current return, you may still have time to file amended returns.
The IRS generally allows taxpayers to amend returns from the past three tax years. This strategy can be particularly valuable if you discover tax benefits you’ve consistently missed, such as education credits, home office deductions, or business expenses.
Amending multiple years of returns can sometimes result in thousands of dollars in refunds.
Pro Tip: Tax and estate planning go hand-in-hand for comprehensive financial security. Just as you review past tax returns, ensure your estate documents are also in order. Where there's a will, there's a way to protect your assets and provide for your loved ones while minimizing tax implications.
6. Seek professional help for complex situations
Professional assistance may be worth the cost if your tax situation involves complicated elements like investment losses, rental properties, cryptocurrency transactions, or business deductions.
A tax professional can often identify deductions and strategies you might miss. While their services typically cost several hundred dollars, the tax savings they uncover can far exceed this investment.
Additionally, professional guidance reduces your audit risk and provides representation if questions arise later.
Pro Tip: Expert advice saves money in many areas of life, including insurance. As tax pros help maximize deductions, insurance comparison tools help minimize premiums. Use a car insurance shopping site and find cheaper insurance. You might save up to $600/yr.
7. Plan for next year while filing this year
Use the extension period to implement tax planning strategies for the current year, potentially saving money on next year’s taxes.
While preparing your extended return, identify opportunities to adjust withholding, increase retirement contributions, or time income and deductions more strategically for the current tax year.
This forward-looking approach can help you avoid needing an extension next year and may reduce your overall tax burden. Small adjustments now can lead to significant tax savings next filing season.
Pro Tip: While planning for next year’s taxes, boost your emergency fund in a high-yield account. Earn as much as possible on your emergency savings. For example, SoFi Checking pays a competitive APY on savings, plus a cash bonus for new members who set up direct deposit. (May change without notice.)
Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account between 10/20/26 and 12/31/27, then within 60 days of account opening receive an eligible direct deposit OR $5,000 or more in qualifying deposits. You must maintain eligible direct deposit or $5,000 in qualifying deposits every 31 days to keep the Boost, for up to 6 months. Rates variable, subject to change.
Terms apply at sofi.com/banking. SoFi Bank, N.A. Member FDIC.
Smart planning pays dividends
Taking full advantage of your tax extension period isn’t just about meeting a deadline—it’s about using this time strategically to ensure you’re not leaving money on the table.
By implementing these strategies, you can transform what might feel like a stressful extension period into a valuable opportunity to optimize your tax situation.
Remember that tax laws change frequently, so strategies that worked in previous years might need adjustment. If your situation is complex, consider consulting with a tax professional, as the savings may likely outweigh the cost of their expertise.
Pro Tip: Smart financial planning includes finding ways to save on everyday expenses. Slash costs on dining, travel, eyeglasses, prescriptions and more with AARP – Just $15/year with auto-renewal. Join now and save hundreds.

Add a Comment