


Navigating the complexities of tax season can be daunting, but with the right strategies, you can significantly enhance your financial standing.
Let’s delve into actionable tips designed to help you optimize your tax returns, maximize deductions, and ultimately retain more of your income. Whether planning for this year or looking ahead, these approaches offer lasting financial benefits.
Pro Tip: Need cash, debt relief, or help funding a major expense? Find the best options tailored to your needs—fast, easy, and secure. Explore financial solutions here.
1. Maximize retirement contributions
Maximizing your contributions to tax-advantaged retirement accounts, such as 401(k)s or traditional IRAs, can significantly lower your taxable income.
This prepares you for a comfortable retirement, and the tax deferral on earnings allows your savings to grow more effectively.
Many miss the chance to contribute the maximum limit each year, thus losing out on immediate tax benefits. Evaluating your budget to prioritize these contributions can make a substantial impact over time.
Pro Tip: Waiting on retirement? Every year costs you. Start today with matched contributions and watch your money grow! Sign up for a SoFi IRA and take advantage of compounding interest so you can retire comfortably. The longer you wait, the less you’ll earn. Get started today.
2. Leverage health savings accounts
Health Savings Accounts (HSAs) are powerful tools if paired with a high-deductible health plan. Contributions are tax-deductible and grow tax-free, and withdrawals for qualified medical expenses are not taxed.
This triple tax advantage makes HSAs a unique savings vehicle. Unused funds roll over yearly, making it effective not just for current but also future medical costs.
If not fully utilized, it’s a missed opportunity to blend health planning with tax savings strategically.
Pro Tip: Maximize your tax savings by utilizing a Health Savings Account if you have a high deductible health plan. Check out Lively HSAs for options available to you.
3. Utilize lifetime learning credit
The Lifetime Learning Credit offers up to $2,000 annually for those pursuing higher education or professional development.
It covers a wide range of educational expenses, and unlike other credits, the number of years you can claim it is unlimited.
Whether you’re updating skills or seeking a career change, this credit supports lifelong learning. Monitoring qualifications and timely claiming can significantly lower your tax liability, making substantial educational goals more feasible.
Pro Tip: Looking for a way to earn income for school expenses with barely any effort? Over $55,000 paid daily to this company's members who take surveys in their free time.
4. Claim the home office deduction
The home office deduction has gained relevance with many transitioning to remote work. This deduction applies to a dedicated working space and can include portions of home expenses like rent, utilities, and maintenance.
Even a small, clearly defined area qualifies. Misconceptions about qualifications lead many to overlook this deduction. By maintaining accurate records, you can reduce your taxable income and align your workspace with savings.
Pro Tip: Save on home expenses with a home warranty. First American covers everything from home appliances to heating and cooling. Take a second and see what policies cost and what they cover.
5. Include charitable contributions
Charitable contributions can benefit both your community and your tax situation. Monetary donations and certain charity-related expenses may be deductible if you itemize. Recent tax changes allow for limited cash contribution deductions even if you take the standard deduction.
Keep detailed receipts and records of all contributions to maximize your tax savings. Freeing up extra money in your budget—such as by lowering recurring expenses—can make giving easier without straining your finances.
Pro Tip: Cut unnecessary costs and free up more for charitable giving. Use a car insurance shopping site to reduce expenses—you could save up to $600 per year.
6. Harvest investment losses
Tax-loss harvesting involves selling underperforming investments to offset gains from other profitable assets. This strategic move can reduce your taxable income, especially in volatile markets.
Reinvesting in assets with better potential while realizing tax benefits can optimize your portfolio.
Understanding the “wash sale” rule is crucial to ensuring compliance, as repurchasing the same investment within 30 days invalidates the initial sale’s tax advantage.
Pro Tip: Diversify investments with real estate through and venture capital with companies like Fundrise. They offer investments as small as $10.
7. Take advantage of child tax credit
Designed to ease families’ financial burdens, the Child Tax Credit can drastically lower tax liabilities for those who qualify. Recent expansions have increased its value, offering up to $2,000 per qualifying child.
Staying informed about eligibility requirements, which adapt to income levels and age limitations, ensures families fully utilize its potential. Routinely updating personal records with changing family dynamics is essential to benefit maximally.
Pro Tip: Protect your family’s financial future with life insurance. Here's a place to get a free, no-obligation quote to ensure you’re prepared for whatever life brings.
8. Deduct student loan interest
Student loans are a significant expense, yet you can deduct up to $2,500 annually in interest paid. This deduction is an above-the-line adjustment, reducing your taxable income.
For graduates managing debt, regularly paying interest can lighten the financial load annually. Understanding income phase-out limits ensures eligibility. Early planning prevents overlooking this beneficial deduction, which many borrowers miss or underutilize.
Pro Tip: Offset student loan expenses through extra income with FreeCash and earn up to $1000 per month doing simple tasks!
9. Optimize state sales tax deduction

If you itemize deductions, deducting state sales tax can be especially beneficial—particularly in states without income taxes. Depending on your spending patterns, this strategy may provide greater savings than deducting state income taxes.
Tracking annual purchases carefully can reveal unexpected tax benefits. Significant expenses like vehicle purchases or home improvements can significantly impact deductible totals, making planning and protecting your financial investments essential.
Pro Tip: If you’re deducting sales tax on a major purchase like a car, protecting that investment is important. Consider an extended car warranty to offset skyrocketing repair costs and avoid unexpected expenses.
10. Utilize energy efficiency credits
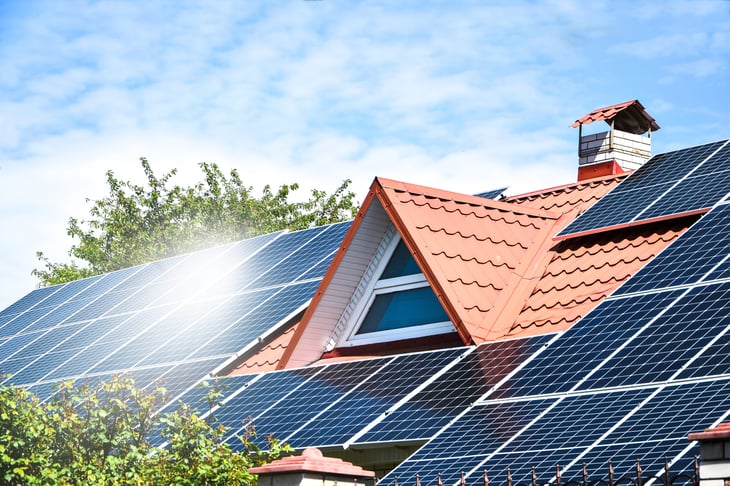
Energy-efficient upgrades at home do more than reduce utility bills—they may also qualify for tax credits. Investments in solar panels, energy-efficient appliances, or improved insulation reduce your carbon footprint and tax bill.
With policies changing annually, keeping abreast of qualifying improvements is key. Green upgrades yield meaningful financial and environmental returns when paired with long-term home value increases.
Pro Tip: Need cash to fund energy-efficient home improvements? Take a minute right now and explore home equity loans. See how much you can get, how fast you can get it and how little you'll pay.
11. Calculate business expenses accurately

For self-employed individuals or small business owners, comprehensive tracking of business expenses is pivotal to minimizing taxable income. Maintaining detailed records, from office supplies to travel and meals, supports claiming maximum deductions.
Beyond immediate savings, this practice streamlines financial reporting and aids in future budgeting. Regular expense evaluation ensures no potential deductions are overlooked, enhancing business profitability.
Pro Tip: Ensure your business affairs are in order. Where there's a will, there's a way helps to secure your assets and protect your family.
12. Account for gambling losses
While gambling winnings are always taxable, failing to deduct losses alongside them can unnecessarily elevate tax bills.
If itemizing, declaring documented losses offsets taxable gains, ensuring only net earnings contribute to tax liabilities.
Understanding the IRS’s strict record-keeping requirements, such as maintaining tickets, receipts, or statements, fosters compliance and benefits those with fluctuating luck.
Pro Tip: Manage and reduce debt stress. If you have more than $20,000 in unsecured debt, get some professional help. National Debt Relief is a trusted source for free advice and assistance.
Steps for future tax success
Implementing these tax strategies can greatly impact your financial bottom line, allowing you to keep more of your hard-earned cash for years to come.
By staying informed and proactive, you protect your wealth and ensure you make the most out of available opportunities.
As you move forward, remember that smart tax planning is not just a seasonal task but a year-round commitment to your financial well-being.
Pro Tip: Explore financial solutions here if you need cash, debt relief, or help funding a major expense. It’s fast, easy, and secure.

Add a Comment