


Money Talks News may earn commission or revenue through links in the content below. Our editorial team independently selects all products. Compensation does not influence our recommendations.
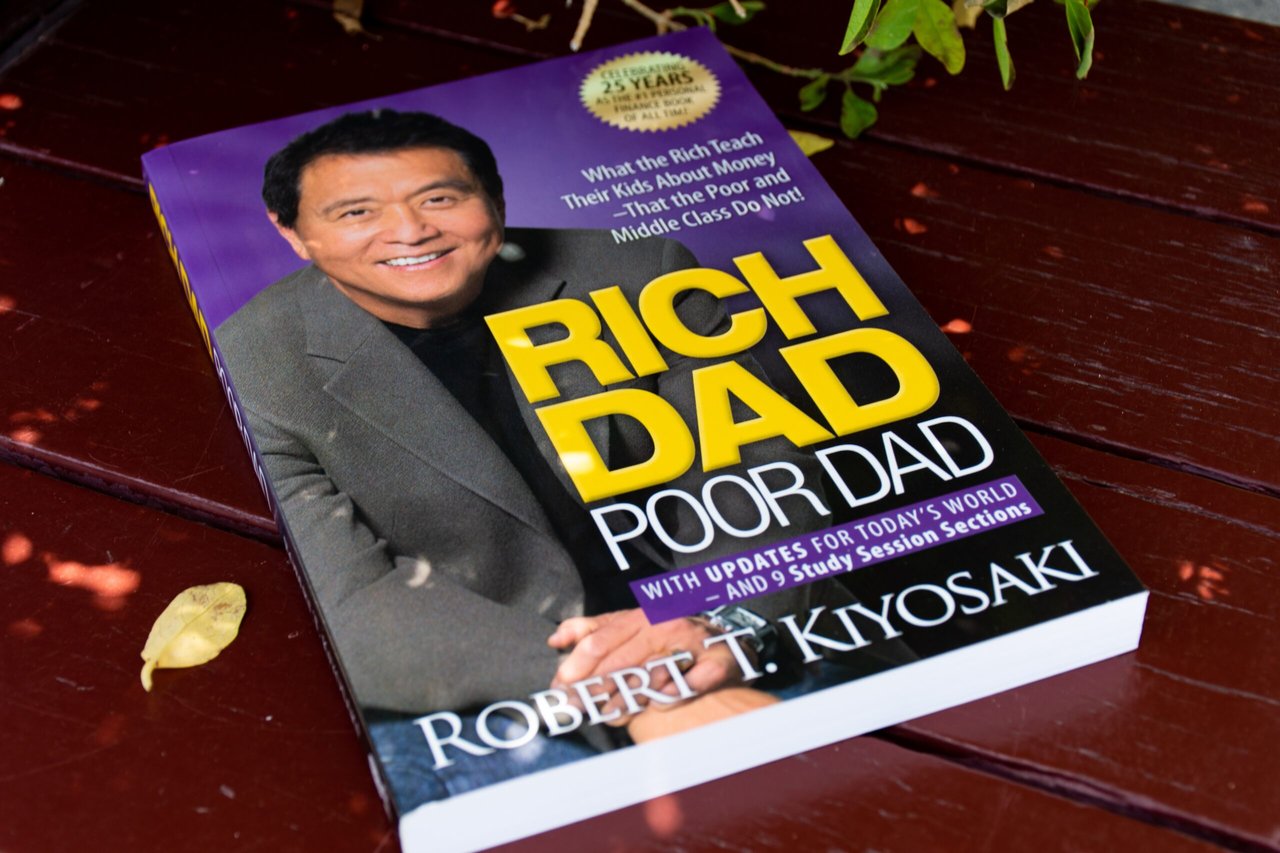
“The boomers are going to be homeless all over the place,” Robert Kiyosaki said this spring. “Your mommy and daddy may be on the street because inflation is going to wipe out their Social Security.” (1)
Here’s the thing: I’m a boomer myself — I’m exactly the person Kiyosaki says is about to get wiped out. I’ve also been a CPA since 1981, and I’ve heard some version of “this is the end” every few years since I started.
Most of those warnings were noise. This one isn’t — not entirely.
A Fortune report out today pegs boomer wealth at nearly $90 trillion, more than half of all household wealth in the country. The same report found the average boomer carries $92,619 in debt, and close to a third of Americans over 55 have nothing saved for retirement. (2)
Adults 55 and older now account for roughly 20% of the 745,652 people counted as homeless on a single January night in 2025. (3)
And Social Security’s retirement trust fund is projected to run dry in late 2032, at which point 78% of scheduled benefits would still be payable. (4)
So Kiyosaki’s standing on something real. But like many people trying to sell you something, he’s just built the wrong argument on top of it.
Here are the five things he gets right, and the two that could wreck you if you believe them.
1. He’s right that the savings math is brutal
About half of Americans 55 and up who have a retirement account have less than $100,000 in it. (2)
So let me do the arithmetic nobody wants to do out loud.
Draw 4% a year from $100,000 and you get $4,000. That’s $333 a month, before taxes. That’s not a retirement income. It’s a car payment.
The cruelty here isn’t that people didn’t save. It’s that most have never run this calculation, so they don’t know how far off they are until they’re 64 and out of runway.
One solution? Long before you reach retirement, talk to a fiduciary investment advisor. They can help you put together a retirement savings strategy, spot tax savings, identify Social Security strategies, and discover planning gaps you’d never see alone.
They might also help you save more. One Vanguard study shows DIY investors turn $500K into $1.7 million over 25 years – while those with advisors reach $3.4 million. You could be missing half your potential wealth.
Finding an expert advisor is easy. For example, SmartAsset instantly matches you with up to three fiduciary advisors – legally required to prioritize your interests.
$100K+ in investments? Get matched free in minutes.
2. He’s right that Social Security won’t be what boomers were promised
The 2026 Trustees Report moved the retirement fund’s depletion date to the fourth quarter of 2032. After that, incoming taxes cover 78% of scheduled benefits. The combined funds hold out to 2034 at 83%. (4)
Nobody’s checks vanish. But a 22% cut is not a rounding error.
On a $2,000 monthly benefit, that’s $440 a month gone. For a retiree whose entire budget is Social Security, that’s the grocery money.
Kiyosaki says inflation will wipe it out. The more accurate version is that Congress will have to choose between cutting benefits and raising taxes, and it’s been avoiding that choice for 30 years.
Plan for less. If more shows up, wonderful — and it’s worth stress-testing your own retirement against that 2032 cut now, while you still have time to adjust.

3. He’s right that inflation is the retiree’s real enemy
This is the part of his argument I have the least trouble with.
A 65-year-old today might be funding 30 years of expenses with money that stopped growing when the paychecks stopped. Even modest inflation cuts purchasing power roughly in half over that stretch.
This is why I own some gold.
Stocks, bonds, funds — when markets stumble, they can sink together. Many investors, me included, diversify with physical gold and silver, tangible assets that have held value for millennia.
Gold or Silver from a source like Anthem Gold Group makes them part of your retirement. And if you use them in an IRA, tax-advantaged. To learn more, Request their free guide — no cost, no obligation, but leave a phone number you’ll actually answer.
Want answers today? Call 888-718-3963 and a specialist can walk you through your options in minutes.
One thing before we keep going — the financial world is louder and dumber than ever. Hot takes everywhere. Almost none of it is worth your time. I’ve spent 35+ years cutting through the noise so you don’t have to. Sign up for the free Money Talks Newsletter — 10 seconds, no spam, just the stuff that matters.
4. He’s right that long-term care can erase a lifetime of saving
Someone turning 65 today has close to a 70% chance of needing long-term care, averaging about three years. (5)
A private nursing home room ran $129,575 a year in the most recent cost survey. (6) Medicare doesn’t cover custodial care — the daily help with bathing, dressing, eating.
I was the executor of my parents’ estate. I’ve seen what these bills do to a balance sheet that looked perfectly healthy on paper.
Three years of care can swallow everything a couple spent 40 years building. This is the most underestimated risk in American retirement, and Kiyosaki is right to be loud about it.
Long-term care insurance helps fill that gap, covering services like home care, assisted living, and help with daily tasks. Rates are typically lowest if you buy in your 50s or early 60s, couples often qualify for discounts, and premiums may even be tax-deductible.
A little planning now can spare your family a difficult financial situation later.
See a list of the best LTC insurance companies — takes 2 minutes.
5. He’s right that ‘house rich, cash poor’ is the boomer trap
Boomers own an enormous share of American housing wealth, and almost none of it pays the light bill.
You can see the strain in the borrowing. Of the roughly 1.8 million home equity lines opened in 2023 and 2024, 57% went to borrowers 50 and older. (2)
That’s not people remodeling kitchens. That’s people reaching for the only large asset they have.
Home equity is real money. It’s just money you have to do something deliberate to reach, and the options all have tradeoffs worth understanding before you sign.
It’s the most common reverse mortgage myth, and it stops a lot of people from looking at their best option. The truth: with a reverse mortgage, you keep the title and stay in your home. The loan simply lets you spend the equity you’ve spent decades building — now, when you need it.
If you’re 62 or older and own your home, Longbridge Financial — a top-rated reverse mortgage lender — offers a free quote showing exactly what you’d qualify for. A licensed specialist then explains what it costs, how repayment works, and what it means for your heirs.
Straight answers, no obligation. Get the facts in about two minutes.
6. Where he’s dangerously wrong: ‘millions’ will be homeless
Let’s do his math for him.
Adults 55 and up make up about 20% of the 745,652 people counted as homeless on that January night. (3) That’s roughly 149,000 people — and it counts everyone over 55, not just boomers.
That’s a real crisis and a national embarrassment. It’s not millions, and it isn’t a forecast of what happens to the typical 68-year-old.
Here’s why the exaggeration matters. Scared people make terrible financial decisions. They sell at bottoms. They buy whatever the person who scared them happens to be selling.
I was a stockbroker on Black Monday in 1987, and I watched that same panic play out again in 2000, in 2008 and in 2020. The panic did more damage than the crash.

7. Where he’s dangerously wrong: his actual prescription
Kiyosaki’s fix is to build your retirement foundation on gold, silver, Bitcoin and Ethereum.
The first two, in moderation, I have no quarrel with. The second two, as a foundation, are how you turn a retirement problem into a retirement catastrophe — which is exactly why crypto in a 401(k) is a risk most people can’t afford once income depends on it.
Bitcoin sat about 49% below its October 2025 record earlier this year, and is now down roughly 28% year to date. (7)
If you’re 45, that’s a rough stretch you can wait out. If you’re 67 and drawing income, a 49% drawdown isn’t volatility. It’s your standard of living, permanently.
I’ve made millions in the stock market. Not by predicting collapses — by owning good companies and refusing to touch them for decades. That’s a boring strategy. Boring is what works when you can’t afford to be wrong.
The bottom line
Kiyosaki has been predicting a depression for as long as I’ve been reading him, and one of these years he’ll be right. That’s how permanent predictions work.
Don’t dismiss the warning, though. The savings gap is real. The Social Security haircut is scheduled. The care costs are coming. Take those seriously and do something concrete about each one.
Just don’t hand your retirement to somebody whose business model requires you to be terrified.
Sources: IBTimes UK (1); Fortune (2); LeadingAge / HUD Annual Homelessness Assessment Report (3); AARP / Social Security Trustees Report (4); Administration for Community Living (5); CareScout / Genworth (6); CCN (7).

Add a Comment