


Editor's Note: This story originally appeared on Boldin.
According to reporting from the Transamerica Center for Retirement Studies, people in the middle class expect diverse sources of retirement income.
How do your financials stack up?
Keep reading to see how your accounts and investment types compare with those of most people.
Note on average versus median: The following average numbers are usually higher than median figures because very wealthy individuals can inflate the average. The median is just the middle number in a set of numbers.
Example: The average of 1, 5 and 10 is 5.3. The median of 1, 5 and 10 is 5.
Total savings
According to the Transamerica research, middle-class retirees reported $186,000 in total household savings excluding home equity (estimated median).
Savings increase with household income.
Those with household income of $50,000 to $99,000 have $120,000 in total savings excluding home equity, compared with those with higher household income of $100,000 to $199,000 who saved $349,000 (estimated medians).
Cash and cash accounts
You want money in cash accounts that you will need for shorter-term living expenses and emergencies.

Average household emergency savings
Emergency savings are needed to cover unexpected financial setbacks, such as unemployment, medical bills, home repairs, auto repairs, and other unexpected expenses.
Emergency savings could also help prevent people from tapping into their retirement savings to cover such expenses.
Transamerica suggests that people in the middle class have saved $8,000 (median) in emergency savings.
Most experts recommend that you have enough emergency cash to cover three to six months of living expenses.

Average household checking accounts
The FDIC reports that 95.5% of U.S. households were “banked” in 2022, meaning that at least one member of the household had a checking or savings account at a bank. This is the highest percentage since the survey began in 2009. They attribute the change to better socioeconomic conditions.
The most recent Survey of Consumer Finances announced that the average household checking balance was $16,891, while the median household checking account balance was $2,800.
Americans ages 55 to 64 have the highest median checking account balance, $3,500.

Average balances across all cash savings or transaction accounts
According to the data from the Federal Reserve, the average savings account balance totals for Americans is $8,000. That amount is what people hold in transaction accounts, which includes checking, savings, money market, call accounts, and prepaid debit cards.
The median balance in all transaction accounts, including savings by age is:
- $5,400 for those under 35
- $7,500 for those between 35 and 44
- $8,700 for those 45 to 54
- $8,000 for those 55 to 64
- $13,400 for those 65 to 74
- Median bank account balances drop off to $10,000 for those 75 and older

Average cash held at home
Since the good old days of the Y2K panic (and before), it has been a common practice for people to keep some amount of cash on hand at home. Whether it is stashed in the mattress or a coffee can in the freezer, cash can be useful in a natural disaster when the grid might be down.
Some experts recommend that you have about three days’ worth of cash to get through a tough spot. Think through what you might absolutely need to buy in a disaster and have that amount on hand.
Although, also remember that keeping cash at home means that the money is not earning returns and is also vulnerable to theft and fire.
Recent trends suggest that younger people are returning to a cash economy.
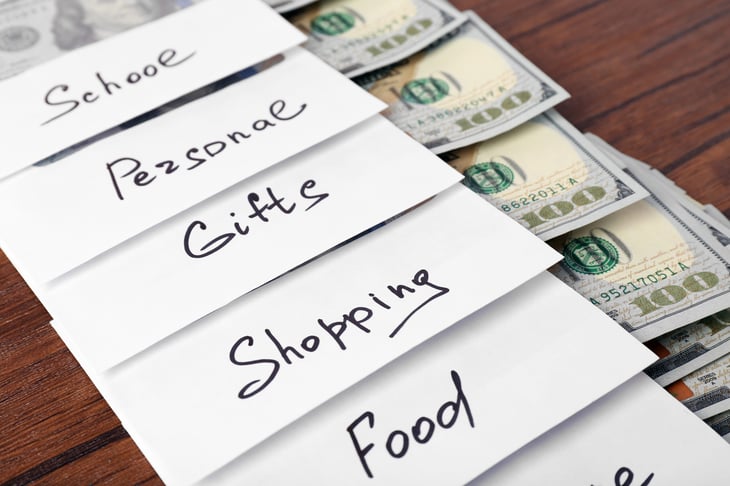
Many are embracing a practice called cash-stuffing. They take their income in cash and store it in envelopes or jars, one container for each category of spending. When a container is depleted, that is it for the month. Recurring bills are paid through a checking account and credit cards are paid off, but from the cash container for credit cards.
Proponents say it is a way to control spending, and one online survey suggests that as many as 61% of adults aged 18-41 use cash-stuffing to some extent.

Health care savings
Almost 3 in 4 people in the middle class (74%) are saving for health care expenses.
Fifty-nine percent are saving in an individual account (e.g., savings, checking, brokerage, etc.), 23% are saving in a health savings account (HSA), 14% are saving in a flexible spending account (FSA), and 4% through other means.
The Employee Benefit Research Institute (ERBI) reports that balances in HSAs are trending upward, but remain relatively low.
End-of-year balances increased in 2022 to $4,607, but average balances are still modest. This may be a result of the fact that many of the HSAs in EBRI’s HSA Database are relatively new. Roughly one-third of the accounts were opened since 2021.

Home equity: 66% of Americans own their homes
Home equity can account for a significant portion of household wealth — growing significantly as people age.
The estimated median home equity for middle-class households is $177,000. Home equity increases with household income. Retirees with household income of $50,000 to $99,000 have $140,000 in home equity, compared with $254,000 in home equity for households with incomes of $100,000 to $199,000.
According to the recent data from the Census Bureau, here is the average home equity by age:
- Under 35 have $60,000 in home equity
- 35-44 have $111,000
- 45-54 have $144,000
- 55-64 have $162,000
- 65 and over have $300,000
Home equity can be a critical component of a retirement plan. This money can be tapped by retirees in a wide variety of effective ways, most commonly through: downsizing.

Average retirement savings
Retirement accounts are tax-advantaged accounts that are typically not used until you are in retirement. In most cases, there are hefty tax penalties for withdrawals made before you are age 59 1/2.
TransAmerica says that the median retirement savings for the middle class is $66,000.
The most recent Federal Reserve Survey of Consumer Finances shows the median account retirement savings by age:
- $18,880 for those under 35 ($49,130 is the average)
- $45,000 for those 35-44 ($141,520 is the average)
- $115,000 for those 45-54 ($313,200 is the average)
- $185,000 for those 55-64 ($537,560 is the average)
- $200,000 for those over 65-74 ($609,230 is the average)
- $130,000 for those over 75 ($462,410 is the average)

Average IRA balance
The Investment Company Institute (ICI) reports that 36% of all Americans have an IRA — the vast majority of those accounts being traditional IRAs as opposed to Roth IRAs or SEP IRAs, SAR-SEP IRAs or Simple IRAs.
However, Roth IRAs are growing in popularity. In fact, it can be a savvy tax strategy to convert money to a Roth IRA.
The Employee Benefit Research Institute (EBRI) reports the following:
- The average IRA balance is $123,973.
- However, IRA accounts that have been held for 20 years or longer are valued at $283,200 on average.
Fidelity puts the average IRA balance at $116,600.

Average amount held in a 401(k), 403(b) or similar plan
Workplace retirement savings plans have become the way Americans save for retirement.
According to the Pension Rights Center, 45% of all workers participate in a workplace retirement plan. They report that the median retirement account balance for all public and private-sector households is $86,900. For households with a worker or spouse aged 55-65, the median balance is $185,000.
In Vanguard’s How America Saves 2024 report, the average balance of defined contribution plans, most of which are 401(k)s, was $134,128 in 2023.
Here are some average 401(k) balances by age from Fidelity:
- $10,500 for those ages 20-29
- $38,400 for those ages 30-39
- $93,400 for those ages 40-49
- $171,400 for those ages 50-59

The most valuable asset is a plan

Odds are that because you are reading this article, you are doing better than the averages — far better. But do you have what is actually perhaps the most valuable and underutilized asset? A plan? A written plan for your retirement finances?
According to Fidelity, only a mere 18% of Americans have a written retirement plan. And, there is significant research suggesting that a plan is the missing link to financial success and confidence.
When you retire, you are no longer living month to month or year to year. In retirement, you are dealing with a finite set of financial resources that need to be utilized to fund the rest of your life. You really do need a plan.
It is easy to create, manage and track a retirement plan with the Boldin Retirement Planner.

Add a Comment